Apple Q4 2025 — The Comeback Quarter That Put “Intelligence” Back in Apple

Apple reported 8% revenue growth to $102.5 billion and a record $28.75 billion in Services, signaling a return to growth after a flat trend. The iPhone 17 launch and deeper ecosystem engagement drove this performance. Guidance for the holiday quarter suggests continued growth, aligning with Apple’s AI ambitions. Investors reacted positively, with a 6% share price increase post-announcement.

TL;DR Summary

Apple finally broke its flat-growth streak.
Revenue climbed 8 % y/y to $102.5 billion, EPS reached $1.85 (+9 %), and Services hit a record $28.75 billion.
Guidance for the holiday quarter calls for +10–12 % growth, reigniting belief that Apple Intelligence is more than a buzzword.
For growth investors, this quarter marks Apple’s return to the AI-led expansion narrative.


Quarter Recap

After four quarters of muted growth, Apple delivered what Tim Cook called “our strongest lineup ever.”
The iPhone 17 launch, deeper ecosystem engagement, and record Services revenue lifted results well above expectations.
Gross margin expanded to 47.2 %, net income rose to $24.2 billion, and Apple declared another $0.26 dividend while continuing aggressive buybacks.

Beyond the numbers, the tone of the call signaled confidence: management expects the December quarter to be the best holiday season in Apple’s history.
That optimism—and the 6 % share-price jump that followed—suggests investors finally see Apple’s AI strategy taking shape.


Key Highlights

  • Services: $28.75 B (+15 %) — now 28 % of total revenue and driving margin expansion.
  • iPhone: $49.0 B (+6 %) — AI-capable models leading upgrade cycle.
  • Mac / iPad: Flat to down slightly as users wait for AI refreshes.
  • Geography: Greater China $14.5 B (+3 %) — showing early stabilization.
  • Guidance: Revenue +10–12 %, gross margin 47–48 % next quarter.

(Note: Apple’s 8 % revenue growth trails Microsoft’s +12 % and Google’s +10 %, but represents its strongest acceleration since 2022.)


How Apple Intelligence Actually Creates Value

For now, “Apple Intelligence” isn’t a separate subscription—it’s a device-pull engine.
AI-driven features such as natural-language photo search, cross-app summaries, and on-device personal assistance require the latest hardware chips (A18, M4).
That design forces upgrades and feeds Services usage. Apple plans to layer paid tiers later, turning AI into a recurring revenue lever by FY 2026.


SWOT Analysis — Estimated Price Impact

Strengths (+6 to +12 %)
A 2.2 billion-device installed base and record Services margin growth create durable pricing power.
AI-ready devices expand average selling prices and lift gross margin.
→ + $15 – $30 per share

Weaknesses (–5 to –10 %)
Hardware still ≈ 48 % of sales; tariffs and China competition pressure margins.
AI monetization lag keeps near-term EPS growth modest.
→ – $13 – $26 per share

Opportunities (+10 to +18 %)
AI integration across devices and services bundles can boost ARPU by 5–8 %.
Emerging-market FinTech and subscriptions expand TAM.
→ + $20 – $36 per share

Threats (–8 to –15 %)
Regulation (EU DMA, App Store fees), supply-chain relocation costs, and AI competition remain real headwinds.
→ – $18 – $32 per share
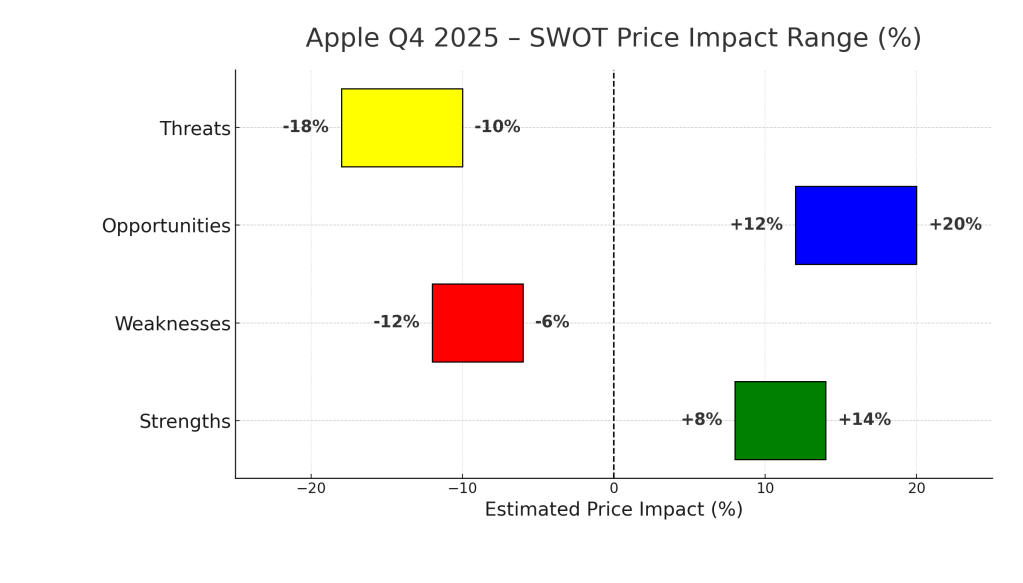
Horizontal SWOT bar chart for Apple Q4 2025 showing the estimated stock-price impact ranges for Strengths, Weaknesses, Opportunities, and Threats. Strengths (green) range from +8% to +14%, Weaknesses (red) from –12% to –6%, Opportunities (blue) from +12% to +20%, and Threats (yellow) from –18% to –10%.

Valuation Scenarios

Apple’s fair value clusters around $270, but outcomes vary depending on how quickly its AI ecosystem monetizes.
Here’s how the road ahead could play out:

  • Bull Case ($305, ~30 % probability):
    Apple executes on AI integration, driving 12 % EPS growth and pushing Services beyond 30 % of total revenue.
    The market rewards it with a premium multiple near 32×.
  • Base Case ($270, ~50 % probability):
    EPS grows about 8 % as AI demand builds gradually.
    The stock trades around 29× earnings — roughly where it sits today.
  • Bear Case ($230, ~20 % probability):
    China softness, regulation, and muted AI monetization limit EPS to +3 %.
    Multiple compresses to 25× as investors rotate to faster-growing peers.

➡️ Fair Value Estimate: ≈ $272.5 per share, balancing these three outcomes.
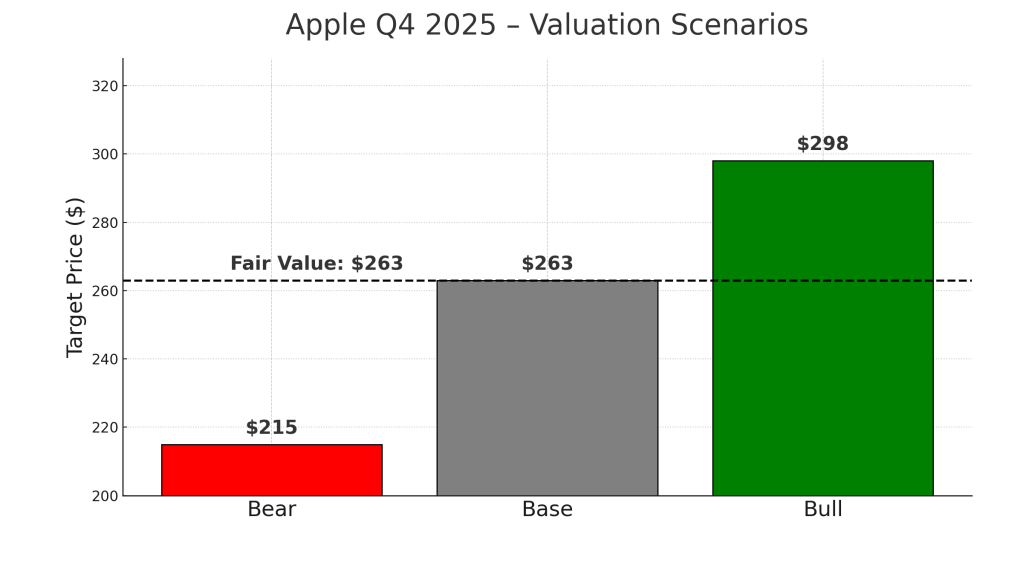
Vertical bar chart for Apple Q4 2025 valuation scenarios showing Bear, Base, and Bull price estimates. Bear scenario (red) is $215, Base (gray) is $263, and Bull (green) is $298. A horizontal dashed line marks Fair Value at $263.

Verdict

At ≈ $270, Apple is fairly valued with a clear path to earnings expansion.
Growth investors should hold core positions and add on dips near $230–240.
The next inflection point arrives mid-2026, when AI features begin contributing revenue and Apple could justify a re-rating to 32–34× P/E ($285–295 target).
If Apple proves that Intelligence sells devices — not just headlines — $300 may come sooner than bears expect.


What to Watch Next

  • Adoption metrics for Apple Intelligence features in real-world use.
  • Services ARPU growth and subscription renewal rates.
  • China unit sales momentum post-holiday quarter.
  • Margin management as $1.4 B tariff cost hits Q1.

(Visual Placeholder #5 – Peer Comparison Table: Apple vs Microsoft vs Alphabet Growth and Margins)


Call to Action

Follow SWOTstock for AI-era earnings analysis of Amazon, Microsoft, and Tesla as we track how AI execution reshapes Big Tech leadership.
Subscribe for alerts when next-quarter AI scorecards drop.


Disclaimer

This analysis uses only Apple Inc.’s official Q4 FY 2025 financial report and earnings call.
It is for informational purposes only and not investment advice.


Berkshire’s Quiet Bet on Alphabet Reinforces the Value Case Behind the $100 B Quarter

Berkshire Hathaway revealed a US $4.3 billion investment in Alphabet Inc. during Q3 2025, buying approximately 17.8 million shares. This strategic move occurred as Alphabet achieved its first US $100 billion revenue quarter. Berkshire’s purchase reflects a value-focused approach amid a tech market rotation, emphasizing Alphabet’s solid fundamentals and growth potential.

Berkshire Hathaway has disclosed a new US $4.3 billion position in Alphabet Inc. (GOOGL), confirming that Warren Buffett’s conglomerate entered the stock during the third quarter of 2025 — the same period in which Alphabet reported its first-ever US $100 billion revenue quarter.

According to Berkshire’s latest 13-F filing, the company purchased roughly 17.8 million shares of Alphabet, making it one of Berkshire’s ten largest equity holdings. The move surprised market watchers who have long associated Berkshire’s tech exposure primarily with Apple, which the firm trimmed in the same quarter.


A Contrarian Entry at a Trillion-Dollar Scale

Berkshire’s timing stands out. Alphabet shares were trading around US $270 – 280 during Q3 2025 — only modestly above their estimated intrinsic value range. While other institutional investors were rotating out of mega-cap tech after two years of outperformance, Berkshire appears to have treated Alphabet as a value compounder rather than a momentum play.

For Buffett followers, the purchase echoes a familiar pattern: buying into a cash-rich franchise once its growth narrative collides with valuation discipline. Alphabet fits that mold neatly — a business generating more than US $80 billion in free cash flow annually, returning US $15 billion in quarterly buybacks, and maintaining over US $100 billion in cash reserves.


Fundamentals Back the Move

Alphabet’s Q3 2025 report, released October 29, underscored that growth and prudence can coexist in Big Tech.

  • Revenue: US $102.3 billion (+16 % YoY)
  • Operating Income: US $31.7 billion (+23 %)
  • EPS: US $2.87
  • Google Cloud: +34 % YoY, margin rising to 9 %
  • CapEx: Raised to US $91 – 93 billion for AI data-center expansion

CEO Sundar Pichai described the period as “a reflection of how AI is transforming every corner of our business,” while CFO Ruth Porat stressed “disciplined long-term investment.”

Those remarks align closely with Buffett’s own playbook — durable cash flow, reinvestment discipline, and capital allocation guided by intrinsic value rather than quarterly optics.


Reinforcing the “Still Underpriced” Thesis

Our prior SWOTstock analysis of Alphabet’s Q3 results placed fair value near US $284 per share, with the market trading just above that level post-earnings. Berkshire’s purchase suggests that even at these prices, long-term investors still see a margin of safety — particularly as Alphabet’s AI infrastructure spending begins to translate into productivity and monetization gains across Search, YouTube, and Cloud.

For value-oriented readers, the implication is clear: when Berkshire buys into a trillion-dollar tech name after a record quarter, it’s not chasing growth — it’s buying durability.


Market Reaction

The disclosure briefly lifted Alphabet shares in after-hours trading on Friday, as investors digested the significance of Berkshire’s first new mega-cap tech stake in years. Analysts now expect fresh comparisons between Alphabet’s AI capital discipline and Apple’s maturing growth profile, which Berkshire has been gradually reducing.

As of mid-November 2025, Alphabet trades around US $277, giving the stake a paper value near its initial cost — a rare instance where Buffett’s patience and Alphabet’s execution appear perfectly aligned.


Disclosure: This article is based on public filings and Alphabet’s official Q3 2025 financial results. It does not constitute investment advice.


Related Post

Cisco Q1 FY 2026 – AI Demand Lifts Guidance, But Valuation Looks Full

Cisco’s fiscal 2026 began strongly, with revenue up 8% to $14.9 billion and non-GAAP EPS up 10% to $1.00. Management raised guidance due to AI orders and Splunk integration. Despite this, Cisco trades above historic valuation levels at $74, making it less attractive for value investors seeking bargains.

🧭 TL;DR Summary

Cisco (CSCO:NASDAQ) delivered a strong start to fiscal 2026: revenue rose 8 % to $14.9 billion and non-GAAP EPS jumped 10 % to $1.00. Management raised full-year guidance on accelerating AI-network orders and early progress integrating Splunk. Yet, after the 6 – 8 % post-earnings surge, Cisco trades well above its historic valuation range. For value investors, it remains a reliable dividend engine—but hardly a bargain at $74.


📅 Quarter Recap

  • Revenue: $14.9 billion (+8 % YoY)
  • GAAP EPS: $0.72 (+6 %)  Non-GAAP EPS: $1.00 (+10 %)
  • Gross Margin: 65.5 % (GAAP) / 68.1 % (non-GAAP)
  • Operating Cash Flow: $3.2 billion (–12 % YoY)
  • Shareholder Returns: $2 billion buybacks + $0.41 dividend
  • Guidance: FY 2026 revenue ≈ $60.6 billion; non-GAAP EPS $4.08 – 4.14

AI-driven switching orders, stronger software renewals, and Splunk integration boosted confidence, while recurring subscription revenue rose to 44 % of total sales—proof that Cisco’s transformation is gaining traction.


🔍 Key Highlights

  • AI Infrastructure Momentum: Backlog > $1 billion in AI network orders.
  • Subscription Strength: Security + observability software sustain recurring growth.
  • Margin Discipline: Gross margins above 65 % despite input inflation.
  • Capital Returns: Consistent buybacks and ~2 % dividend yield signal balance-sheet strength.
  • Execution Watch: Operating cash flow fell 12 %, and analysts seek clearer AI-revenue disclosure before assigning higher multiples.

💪 SWOT Analysis (with estimated price impact ranges)

Strengths (+8 % to +12 %)
Cisco’s expanding recurring-revenue base and tight cost control anchor earnings stability. Its balance sheet is debt-light and supports steady buybacks and dividends—attributes valued by income investors.

Weaknesses (–5 % to –8 %)
Hardware still drives over 40 % of sales, leaving results exposed to ordering cycles. Operating cash flow slid 12 %, reflecting inventory timing and working-capital drag. Without transparent AI-revenue reporting and faster cash-conversion, valuation upside is hard to justify.

Opportunities (+10 % to +15 %)
AI-infrastructure spending offers a fresh growth lane. The Silicon One platform and Splunk integration can unlock new data and security use cases, while Hypershield subscriptions could lift software margins 1 – 2 points. Execution on these fronts may re-rate Cisco toward 15× earnings.

Threats (–7 % to –10 %)
Rivals such as Arista, Palo Alto Networks, and Juniper’s Mist unit are capturing AI-network share faster. Cisco’s portfolio breadth can appear complex to customers seeking simpler cloud-native solutions. Macro slowdown or AI-capex pause would test both hardware and optics segments.

Horizontal bar chart titled ‘Cisco Q1 FY 2026 – SWOT Price Impact Range ($)’. The chart shows estimated price impact ranges for Strengths (+8 to +12, green), Weaknesses (–8 to –5, red), Opportunities (+10 to +15, blue), and Threats (–10 to –7, yellow). Vertical dashed line at zero with horizontal axis from –20 to 20 dollars, representing balanced upside and downside factors.

📈 Valuation Scenarios (Based on FY 2026 Guidance)

Bull Case (~30 % probability)

  • AI network revenue grows +10 %, software margins expand 100 bps.
  • EPS ≈ $4.20, 15× multiple → fair value ≈ $63.
  • Requires strong backlog conversion and clear AI execution proof.

Base Case (~50 %)

  • 6 % steady growth, EPS ≈ $4.10, 14× multiple → fair value ≈ $57.
  • Most probable path given guidance and macro conditions.

Bear Case (~20 %)

  • Flat revenue and AI order delays, EPS ≈ $3.80, 12× multiple → fair value ≈ $46.
  • Reflects execution or macro slippage.

Weighted Fair Value: ≈ $58 per share (~8 % below current $74 price).

Bar chart titled ‘Cisco Q1 FY 2026 – Valuation Scenarios’. The Bear case shows $46 (20 %, red bar), the Base case shows $57 (50 %, gray bar), and the Bull case shows $63 (30 %, green bar). A horizontal dashed line marks the probability-weighted fair value at approximately $56.6, labeled in purple text.

🔭 Forward Checkpoints to Monitor

  • Q2 AI-network bookings growth and conversion rate.
  • Recurring revenue as % of total (45 % target watch).
  • Cash-flow recovery trend and Splunk synergy delivery.
  • Competitive pricing in Ethernet and optics segments.

💡 Verdict

Cisco’s AI story is credible but largely priced in. At ~18× forward earnings, shares sit above their five-year average. Cash generation remains solid and the dividend safe, yet the margin of safety is thin after the rally.

  • Fair Price: ≈ $58 / share
  • Buy-Under Level: ≈ $55
  • Action: Hold for income; wait for a pullback before adding.

📣 Call to Action

Dividend investors should keep Cisco on their watchlist but avoid chasing momentum. Add on weakness below $55 to lock in a better yield and valuation margin.


⚖️ Disclaimer

This analysis is based solely on Cisco Systems’ official Q1 FY 2026 financial report and earnings call materials. It is for informational purposes only and not investment advice. Always verify figures with official sources and consider personal risk tolerance before investing.