Berkshire’s Quiet Bet on Alphabet Reinforces the Value Case Behind the $100 B Quarter

Berkshire Hathaway revealed a US $4.3 billion investment in Alphabet Inc. during Q3 2025, buying approximately 17.8 million shares. This strategic move occurred as Alphabet achieved its first US $100 billion revenue quarter. Berkshire’s purchase reflects a value-focused approach amid a tech market rotation, emphasizing Alphabet’s solid fundamentals and growth potential.

Berkshire Hathaway has disclosed a new US $4.3 billion position in Alphabet Inc. (GOOGL), confirming that Warren Buffett’s conglomerate entered the stock during the third quarter of 2025 — the same period in which Alphabet reported its first-ever US $100 billion revenue quarter.

According to Berkshire’s latest 13-F filing, the company purchased roughly 17.8 million shares of Alphabet, making it one of Berkshire’s ten largest equity holdings. The move surprised market watchers who have long associated Berkshire’s tech exposure primarily with Apple, which the firm trimmed in the same quarter.


A Contrarian Entry at a Trillion-Dollar Scale

Berkshire’s timing stands out. Alphabet shares were trading around US $270 – 280 during Q3 2025 — only modestly above their estimated intrinsic value range. While other institutional investors were rotating out of mega-cap tech after two years of outperformance, Berkshire appears to have treated Alphabet as a value compounder rather than a momentum play.

For Buffett followers, the purchase echoes a familiar pattern: buying into a cash-rich franchise once its growth narrative collides with valuation discipline. Alphabet fits that mold neatly — a business generating more than US $80 billion in free cash flow annually, returning US $15 billion in quarterly buybacks, and maintaining over US $100 billion in cash reserves.


Fundamentals Back the Move

Alphabet’s Q3 2025 report, released October 29, underscored that growth and prudence can coexist in Big Tech.

  • Revenue: US $102.3 billion (+16 % YoY)
  • Operating Income: US $31.7 billion (+23 %)
  • EPS: US $2.87
  • Google Cloud: +34 % YoY, margin rising to 9 %
  • CapEx: Raised to US $91 – 93 billion for AI data-center expansion

CEO Sundar Pichai described the period as “a reflection of how AI is transforming every corner of our business,” while CFO Ruth Porat stressed “disciplined long-term investment.”

Those remarks align closely with Buffett’s own playbook — durable cash flow, reinvestment discipline, and capital allocation guided by intrinsic value rather than quarterly optics.


Reinforcing the “Still Underpriced” Thesis

Our prior SWOTstock analysis of Alphabet’s Q3 results placed fair value near US $284 per share, with the market trading just above that level post-earnings. Berkshire’s purchase suggests that even at these prices, long-term investors still see a margin of safety — particularly as Alphabet’s AI infrastructure spending begins to translate into productivity and monetization gains across Search, YouTube, and Cloud.

For value-oriented readers, the implication is clear: when Berkshire buys into a trillion-dollar tech name after a record quarter, it’s not chasing growth — it’s buying durability.


Market Reaction

The disclosure briefly lifted Alphabet shares in after-hours trading on Friday, as investors digested the significance of Berkshire’s first new mega-cap tech stake in years. Analysts now expect fresh comparisons between Alphabet’s AI capital discipline and Apple’s maturing growth profile, which Berkshire has been gradually reducing.

As of mid-November 2025, Alphabet trades around US $277, giving the stake a paper value near its initial cost — a rare instance where Buffett’s patience and Alphabet’s execution appear perfectly aligned.


Disclosure: This article is based on public filings and Alphabet’s official Q3 2025 financial results. It does not constitute investment advice.


Related Post

Cisco Q1 FY 2026 – AI Demand Lifts Guidance, But Valuation Looks Full

Cisco’s fiscal 2026 began strongly, with revenue up 8% to $14.9 billion and non-GAAP EPS up 10% to $1.00. Management raised guidance due to AI orders and Splunk integration. Despite this, Cisco trades above historic valuation levels at $74, making it less attractive for value investors seeking bargains.

🧭 TL;DR Summary

Cisco (CSCO:NASDAQ) delivered a strong start to fiscal 2026: revenue rose 8 % to $14.9 billion and non-GAAP EPS jumped 10 % to $1.00. Management raised full-year guidance on accelerating AI-network orders and early progress integrating Splunk. Yet, after the 6 – 8 % post-earnings surge, Cisco trades well above its historic valuation range. For value investors, it remains a reliable dividend engine—but hardly a bargain at $74.


📅 Quarter Recap

  • Revenue: $14.9 billion (+8 % YoY)
  • GAAP EPS: $0.72 (+6 %)  Non-GAAP EPS: $1.00 (+10 %)
  • Gross Margin: 65.5 % (GAAP) / 68.1 % (non-GAAP)
  • Operating Cash Flow: $3.2 billion (–12 % YoY)
  • Shareholder Returns: $2 billion buybacks + $0.41 dividend
  • Guidance: FY 2026 revenue ≈ $60.6 billion; non-GAAP EPS $4.08 – 4.14

AI-driven switching orders, stronger software renewals, and Splunk integration boosted confidence, while recurring subscription revenue rose to 44 % of total sales—proof that Cisco’s transformation is gaining traction.


🔍 Key Highlights

  • AI Infrastructure Momentum: Backlog > $1 billion in AI network orders.
  • Subscription Strength: Security + observability software sustain recurring growth.
  • Margin Discipline: Gross margins above 65 % despite input inflation.
  • Capital Returns: Consistent buybacks and ~2 % dividend yield signal balance-sheet strength.
  • Execution Watch: Operating cash flow fell 12 %, and analysts seek clearer AI-revenue disclosure before assigning higher multiples.

💪 SWOT Analysis (with estimated price impact ranges)

Strengths (+8 % to +12 %)
Cisco’s expanding recurring-revenue base and tight cost control anchor earnings stability. Its balance sheet is debt-light and supports steady buybacks and dividends—attributes valued by income investors.

Weaknesses (–5 % to –8 %)
Hardware still drives over 40 % of sales, leaving results exposed to ordering cycles. Operating cash flow slid 12 %, reflecting inventory timing and working-capital drag. Without transparent AI-revenue reporting and faster cash-conversion, valuation upside is hard to justify.

Opportunities (+10 % to +15 %)
AI-infrastructure spending offers a fresh growth lane. The Silicon One platform and Splunk integration can unlock new data and security use cases, while Hypershield subscriptions could lift software margins 1 – 2 points. Execution on these fronts may re-rate Cisco toward 15× earnings.

Threats (–7 % to –10 %)
Rivals such as Arista, Palo Alto Networks, and Juniper’s Mist unit are capturing AI-network share faster. Cisco’s portfolio breadth can appear complex to customers seeking simpler cloud-native solutions. Macro slowdown or AI-capex pause would test both hardware and optics segments.

Horizontal bar chart titled ‘Cisco Q1 FY 2026 – SWOT Price Impact Range ($)’. The chart shows estimated price impact ranges for Strengths (+8 to +12, green), Weaknesses (–8 to –5, red), Opportunities (+10 to +15, blue), and Threats (–10 to –7, yellow). Vertical dashed line at zero with horizontal axis from –20 to 20 dollars, representing balanced upside and downside factors.

📈 Valuation Scenarios (Based on FY 2026 Guidance)

Bull Case (~30 % probability)

  • AI network revenue grows +10 %, software margins expand 100 bps.
  • EPS ≈ $4.20, 15× multiple → fair value ≈ $63.
  • Requires strong backlog conversion and clear AI execution proof.

Base Case (~50 %)

  • 6 % steady growth, EPS ≈ $4.10, 14× multiple → fair value ≈ $57.
  • Most probable path given guidance and macro conditions.

Bear Case (~20 %)

  • Flat revenue and AI order delays, EPS ≈ $3.80, 12× multiple → fair value ≈ $46.
  • Reflects execution or macro slippage.

Weighted Fair Value: ≈ $58 per share (~8 % below current $74 price).

Bar chart titled ‘Cisco Q1 FY 2026 – Valuation Scenarios’. The Bear case shows $46 (20 %, red bar), the Base case shows $57 (50 %, gray bar), and the Bull case shows $63 (30 %, green bar). A horizontal dashed line marks the probability-weighted fair value at approximately $56.6, labeled in purple text.

🔭 Forward Checkpoints to Monitor

  • Q2 AI-network bookings growth and conversion rate.
  • Recurring revenue as % of total (45 % target watch).
  • Cash-flow recovery trend and Splunk synergy delivery.
  • Competitive pricing in Ethernet and optics segments.

💡 Verdict

Cisco’s AI story is credible but largely priced in. At ~18× forward earnings, shares sit above their five-year average. Cash generation remains solid and the dividend safe, yet the margin of safety is thin after the rally.

  • Fair Price: ≈ $58 / share
  • Buy-Under Level: ≈ $55
  • Action: Hold for income; wait for a pullback before adding.

📣 Call to Action

Dividend investors should keep Cisco on their watchlist but avoid chasing momentum. Add on weakness below $55 to lock in a better yield and valuation margin.


⚖️ Disclaimer

This analysis is based solely on Cisco Systems’ official Q1 FY 2026 financial report and earnings call materials. It is for informational purposes only and not investment advice. Always verify figures with official sources and consider personal risk tolerance before investing.


💡 Alphabet Q3 2025 Earnings — A $100 B Quarter that Still Feels Underpriced

Alphabet (GOOGL) achieved over $100 billion in quarterly revenue for the first time, showing 16% year-over-year growth. Key drivers include a strong Cloud business and effective YouTube monetization. Despite CapEx concerns, the company remains cash-rich, positioning itself for long-term growth in AI and other sectors, recommending a hold strategy.

TL;DR Summary

Alphabet (GOOGL:NASDAQ) just passed the $100 billion quarterly revenue mark for the first time — growing 16 % year over year with broad strength across Search, YouTube, and Cloud. Despite record profits, the stock still trades near fair value, offering patient investors a long-term compounding story powered by disciplined AI execution.


Q3 2025 Financial Highlights

  • Revenue: $102.3 B (+16 % YoY)
  • Operating Income: $31.7 B (+23 %)
  • EPS: $2.87 (diluted)
  • Google Cloud: $15.2 B (+34 %), operating margin 9 % (up from 5 %)
  • YouTube Ads: +18 % YoY, Shorts monetization gaining traction
  • Buybacks: $15 B this quarter
  • CapEx: Guidance raised to $91–93 B (from $85 B) to expand AI infrastructure

Management Commentary — The AI Era at Work

CEO Sundar Pichai described the quarter as “a reflection of how AI is transforming every corner of our business.”
He highlighted how Gemini models are now woven across Search, Workspace, and Android, while Google Cloud has become “a foundation for the next wave of AI applications.”

Pichai also drew attention to Waymo’s momentum, noting tens of thousands of fully autonomous rides weekly — a reminder that Alphabet’s portfolio still holds long-term optionality beyond advertising.
CFO Ruth Porat reiterated a focus on “disciplined investment” and sustainable capital returns, ensuring AI expansion doesn’t come at the expense of profitability.


Market Reaction

Shares rose roughly 6 % post-earnings to around $288, as investors applauded Alphabet’s combination of growth and cost control.
Growth investors celebrated the $100 B milestone; value investors noticed something quieter but more powerful — free-cash-flow compounding and balance-sheet strength, with over $100 B in cash and a business model that still prints double-digit operating margins despite surging AI spend.


SWOT Analysis — What’s Driving and Challenging Alphabet

Strengths — The Engine Still Scales

  • Alphabet’s ability to integrate AI across core products has turned efficiency into a margin lever, driving a 23 % jump in operating income.
  • Cloud growth of +34 % confirms enterprise adoption of Google AI and Vertex AI, while YouTube continues to monetize Shorts effectively.
  • A balance sheet boasting $109 B in cash and $80 B in free cash flow gives management the flexibility to invest and repurchase shares without financial strain.
  • These elements together could support a 6 – 12 % upside in valuation, equivalent to +$16–32 per share, if current trends hold.

Weaknesses — Spending Before the Payoff

  • The biggest risk near term is CapEx intensity: management raised 2025 guidance to $91–93 B, pushing short-term margins down to 31 %.
  • Cloud infrastructure build-out and TPU chip development consume cash before incremental revenue arrives.
  • For value investors, this is the “patience tax” — reinvestment that depresses earnings temporarily but is critical to maintain AI leadership. Estimated drag: −6 to −10 % on near-term fair value.

Opportunities — Optionality Beyond Ads

  • The rollout of Gemini-powered experiences across Search and Workspace is still early. If user engagement and monetization scale as expected, Alphabet could open entirely new revenue lines within existing products.
  • Waymo’s commercialization offers an overlooked lever: as autonomous rides expand to new cities, the segment could evolve from cost center to strategic asset.
  • Together, these trends imply +8 to +15 % potential uplift as new businesses begin contributing meaningfully.

Threats — The Unseen Headwinds

  • Alphabet faces regulatory pressure in the U.S. and EU that could reshape how it structures Search partnerships.
  • Rising AI training costs and limited chip supply could inflate unit economics in 2026.
  • Global digital tax initiatives also threaten to trim net margins.
  • These could shave 10 – 18 % off valuation in a downside scenario.
Bar chart showing Alphabet Q3 2025 SWOT price impact ranges: Strengths (+16 to +32 USD, green), Weaknesses (−28 to −17 USD, red), Opportunities (+23 to +40 USD, blue), and Threats (−50 to −28 USD, yellow), with a dashed vertical line at zero indicating estimated stock price effects.

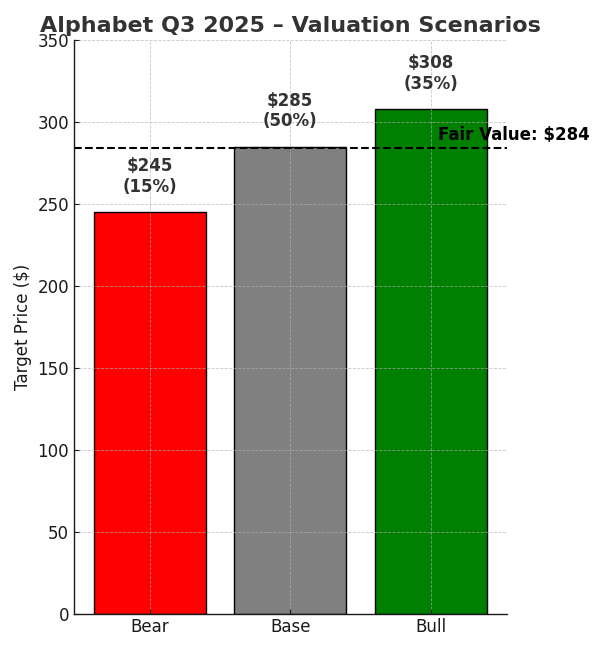
Valuation Scenarios — Fair Value Still Around $284

Bull Case (35 % probability)
If Gemini monetization accelerates and Cloud margins surpass 10 %, EPS could reach $14 in FY 2026. At 22× earnings, that implies a $308 target — driven by full AI adoption and modest multiple expansion.

Base Case (50 % probability)
A more realistic view assumes 12 % revenue growth and modest margin recovery. With EPS near $13 and 20× multiple, fair value sits at $285 — consistent with steady compounding and disciplined reinvestment.

Bear Case (15 % probability)
If regulatory constraints slow Search deals or AI costs balloon, EPS might stall around $12. Applying 17× multiple yields $245 per share.
Even here, Alphabet remains profitable and cash-rich, limiting true downside risk.

Weighted Fair Value: ≈ $284/share — almost identical to where the stock trades now (~$288).
For long-term holders, that suggests limited short-term upside but strong margin of safety given cash reserves and buyback velocity.

Vertical bar chart showing Alphabet Q3 2025 valuation scenarios: Bear case $245 (15%), Base case $285 (50%), and Bull case $308 (35%), with a dashed horizontal line marking fair value at $284 per share.

Verdict — Hold, Accumulate Below $270

Alphabet remains a quiet compounding engine: dominant in AI infrastructure, prudent in spending, and generous in shareholder returns.
At $288, the stock sits near intrinsic value. But below $270, its 3.5 % free-cash-flow yield and recurring revenue make it a compelling long-term hold for patient investors.

For value investors, the strategy is clear: own quality, wait through the CapEx cycle, and let compounding do the work.


What to Watch Next

  • Gemini monetization in Search and YouTube
  • Cloud profitability progression toward 10 %+ margins
  • DOJ antitrust outcomes and global tax rulings
  • Returns from AI infrastructure CapEx and Waymo expansion

Call to Action

Follow SWOTstock for clear, fundamentals-based coverage of high-cash-flow AI compounders like Alphabet, Microsoft, and Amazon.
Subscribe to receive new posts right after each earnings call.


Disclaimer

This analysis is based solely on Alphabet Inc. official Q3 2025 financial report and earnings call transcript.
It is not investment advice. Please conduct independent research before investing.


One response to “💡 Alphabet Q3 2025 Earnings — A $100 B Quarter that Still Feels Underpriced”

Leave a comment