Bank of America Q3 2026: Core Banking Holds Up, but the Valuation Case Has Changed

Bank of America reported Q3 earnings with $30 billion in revenue and $6.9 billion net income, impacted by a regulatory settlement charge. Net interest income rose, but Global Markets revenue fell significantly. The revised fair value estimate of $51.36 per share aligns closely with its recent market close, reflecting ongoing challenges.

TL;DR

Bank of America’s lending, net interest income and wealth business remained productive in Q3. Credit losses eased from Q2. Yet weaker capital-markets earnings, a regulatory settlement and a larger gap between the cost and market value of its securities make the previous $63.50 fair-value estimate harder to defend. Our revised probability-weighted estimate is $51.36 per share, approximately equal to the post-earnings closing price.

Quarter Recap

Bank of America reported $30.0 billion in revenue, $6.9 billion in net income and $0.91 in diluted earnings per sharefor the quarter ended September 30, 2026. Results included a $1.2 billion non-tax-deductible regulatory settlement charge, which reduced EPS by $0.17. Excluding that charge, the bank reported adjusted EPS of $1.08 and a 14.9% return on tangible common equity, compared with 17.03% reported ROTCE in Q2.

The core banking figures deserve attention alongside the lower profit. Net interest income increased from $16.0 billion in Q2 to $16.4 billion, while the annualized net charge-off ratio declined from 0.47% to 0.44%. Wealth-management revenue also rose. The sharpest sequential change was in Global Markets: revenue fell from $8.0 billion to $5.9 billion, and segment net income fell from $2.6 billion to $1.2 billion.

Market Reaction

BAC closed at $53.96 before the earnings release and $51.39 on October 14, a decline of 4.76%. An 11:30 a.m. Eastern quote of $50.255 shows that the shares were lower earlier in the session before recovering part of the decline by the close. That price pattern records a negative first-day reaction; it does not tell us how much weight investors assigned to any individual disclosure.

Key Highlights

  • Net interest income continued to grow. BAC attributed the sequential increase partly to fixed-rate asset repricing, loan growth, Global Markets activity and an extra day of interest accrual. The last factor is a reason to avoid treating the entire quarterly increase as a permanent run rate.
  • Credit metrics improved from Q2. Net charge-offs fell to $1.35 billion from $1.41 billion, although an investor still needs to test what happens if losses rise from today’s level.
  • The securities portfolio became a more consequential valuation question. Gross unrealized losses on debt securities increased from $85.3 billion at June 30 to $109.2 billion at September 30. Most of the September amount relates to held-to-maturity securities. These are not an immediate $109.2 billion earnings charge, but persistent marks can constrain flexibility and influence the price an investor will pay for tangible book value.

SWOT Analysis

Strengths. BAC’s deposit and lending franchise continued to produce higher net interest income, while Q3 charge-offs declined. If $0.5–1.0 billion of additional annual pretax income proves durable, our earnings sensitivity suggests approximately 1.1–2.4% more value relative to the prior $63.50 estimate. A similar 1.1–2.4% represents the value protected if annual credit expense stays below a more adverse case. These are conditional model effects, not gains to add to the quarter’s reported earnings.

Weaknesses. Global Markets’ steep sequential decline makes its sustainable contribution harder to judge. If the shortfall ultimately means $1–2 billion less annual pretax income than previously assumed, the estimated value impact is −2.2% to −4.7%. The settlement’s direct EPS cost is $0.17; the longer-term issue is whether remediation produces recurring expense. A hypothetical $0.5–1.0 billion of additional annual pretax cost would imply another −1.1% to −2.4%. BAC has not forecast that recurring cost.

Opportunities. Wealth-management revenue reached $7.1 billion, supported by higher asset-management fees and client flows. A sustained $0.5–1.0 billion annual pretax earnings improvement over our previous normalized case would imply +1.1% to +2.4% in estimated value. BAC also estimates that a 100-basis-point upward parallel shift from its September 30 forward-rate curve would add $1.4 billion to next-12-month net interest income—an earnings sensitivity equivalent to roughly +3.1% to +3.3% of the prior value if sustained. That company estimate is an NII sensitivity, not a forecast of total profit.

Threats. The securities marks raise the possibility that investors demand a lower multiple of tangible book value. A hypothetical 0.05–0.15× multiple reduction equates to approximately −2.3% to −6.9% of the prior value; this is a valuation judgment, not an assumed realization of the securities losses. Credit remains another downside test: a 0.10–0.20 percentage-point increase in the annual charge-off rate on BAC’s current average loans could represent approximately $1.2–2.5 billion in additional annual losses before offsets, or −2.7% to −5.8% in our earnings sensitivity. Q3’s reported charge-offs did not show that deterioration.

These SWOT percentages measure separate, potentially overlapping changes against the old $63.50 valuation reference. They are not forecasts of BAC’s share-price move and should not be summed.

Valuation Scenarios

For a value investor, the question is what BAC can earn sustainably on its tangible equity. Starting with Q3 tangible book value of $29.14 per share, we apply different price-to-tangible-book multiples and cross-check them against normalized earnings. The earnings, multiples and probabilities are our assumptions, not BAC guidance.

ScenarioWhat must happenValuationFair valueProbability
BearWeaker capital-markets income persists; credit and compliance costs rise1.25× tangible book$36.4325%
BaseCore income holds; markets recover partly; ROTCE settles near 14–15%1.80× tangible book$52.4550%
BullMarkets recover more fully; BAC sustains roughly 16–17% ROTCE2.20× tangible book$64.1125%

Probability weighting produces $51.36 per share, versus our previous $63.50 estimate. Q3 tangible book value changed only modestly from Q2’s $29.37; most of the revision reflects a lower multiple for the range of sustainable outcomes and risks we now underwrite. The original Q2 scenario assumptions are unavailable, so this is a fresh valuation rather than a line-by-line revision of that model.

At the $51.39 October 14 close, BAC traded almost exactly at the new weighted estimate. The bear case is about 29% below that price, while the bull case is about 25% above it. The franchise remains valuable, but this price offers little room for our assumptions to be wrong.

What to Watch Next

The next results need to answer three questions: Does net interest income remain durable after adjusting for calendar and rate effects? Does Global Markets regain a dependable earnings contribution? And do securities marks and compliance costs stop putting pressure on the value of the franchise? Those answers matter more to this value case than a one-day share-price recovery.

Disclaimer

This article is independent analysis for educational purposes, not personalized investment advice. Scenario values and SWOT sensitivities depend on stated assumptions and may differ substantially from realized outcomes. ROTCE, tangible book value and several adjusted figures cited above are non-GAAP measures; consult BAC’s reconciliations alongside its reported results.
Bank of America Q2 2026 Earnings Analysis: Strong Core Banking Franchise Supports Higher Fair Value

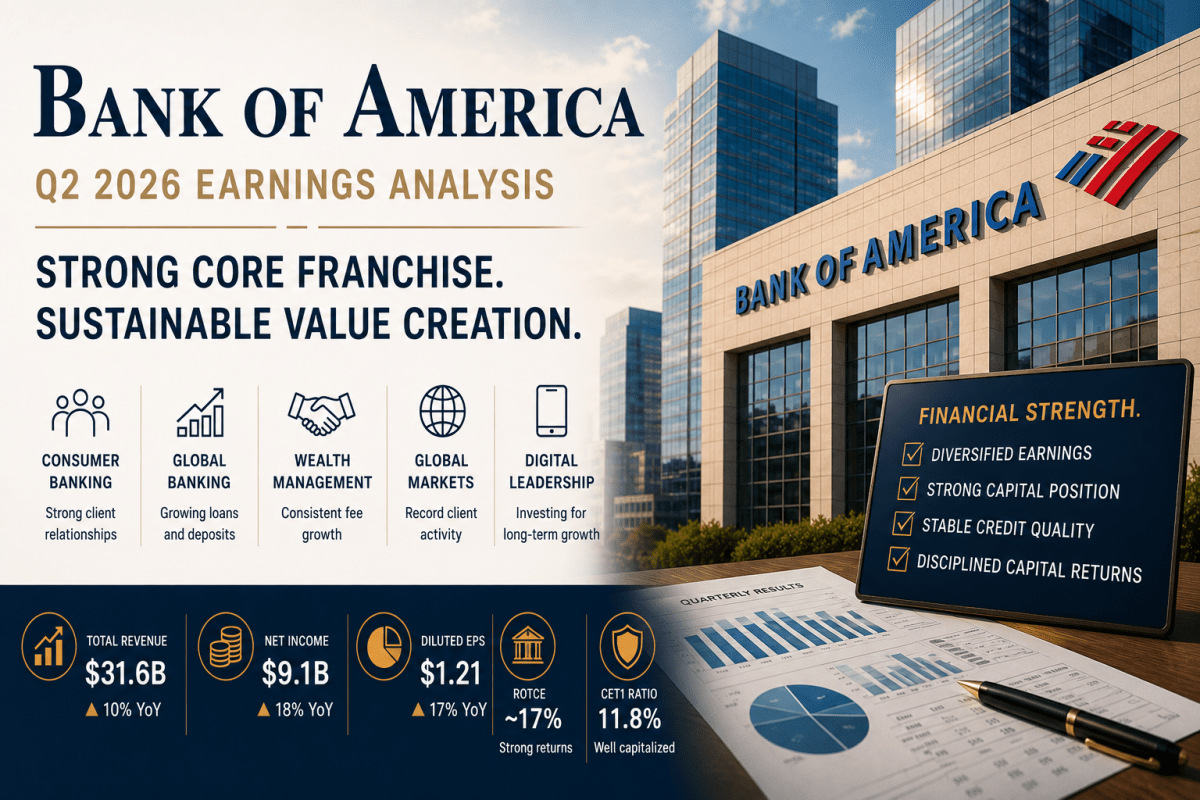
Bank of America reported a robust second quarter with revenues of $31.6 billion and net income of $9.1 billion, reflecting strong performance across its diverse business segments. Despite initial market caution, the company’s earnings stability and growth in net interest income suggest long-term resilience. The estimated fair value of shares is approximately $64.

TL;DR Summary

Bank of America (BAC:NYSE) delivered an impressive second quarter, reporting strong revenue and earnings growth driven by broad-based contributions across Consumer Banking, Wealth Management, Global Banking, and Global Markets. More importantly, the company’s core banking franchise continued to strengthen through growing net interest income, stable credit quality, and robust capital generation.

While the market initially reacted cautiously before the shares recovered during the trading session, our independent analysis suggests the quarter reinforced the long-term investment thesis rather than fundamentally changing it. We estimate a probability-weighted fair value of approximately $64 per share, indicating the stock is modestly undervalued but not yet a “fat pitch.”


Quarter Recap

Bank of America reported another strong quarter that highlighted the resilience of its diversified business model. Revenue reached $31.6 billion, while net income increased to $9.1 billion, resulting in diluted earnings per share of $1.21.

Unlike quarters where performance depends heavily on one business segment, Q2 demonstrated strength across multiple earnings engines. Consumer Banking continued to benefit from healthy client activity, Wealth Management generated steady fee income, Global Banking experienced improved commercial engagement, and Global Markets delivered strong client-driven trading results.

Perhaps more importantly for long-term investors, management reaffirmed confidence in net interest income growth and reported stable credit quality, suggesting that the company’s earnings strength extends beyond short-term market activity.


Key Highlights

  • Revenue increased to $31.6 billion.
  • Net income reached $9.1 billion.
  • Diluted EPS increased to $1.21.
  • Net interest income continued to grow, with management expecting full-year results toward the upper end of previous guidance.
  • ROTCE remained around 17%, demonstrating efficient capital utilization.
  • Consumer and commercial credit quality remained stable.
  • Capital ratios continued to support dividends, share repurchases, and future growth investments.

SWOT Analysis

Bank of America’s latest quarter reinforces the strength of one of the largest banking franchises in the United States. The company continues to benefit from a diversified earnings base, disciplined capital management, and a stable deposit franchise. However, banking remains inherently cyclical, and investors should continue monitoring interest rates, credit quality, and economic conditions.

Strengths

  • Diversified earnings franchise (+8% to +12%)
    • Strong contributions from Consumer Banking, Wealth Management, Global Banking, and Global Markets reduce dependence on any single business segment.
  • Growing core net interest income (+6% to +10%)
    • Continued NII growth reinforces the recurring earnings power of the core banking business.
  • Excellent profitability and capital efficiency (+5% to +8%)
    • ROTCE around 17% demonstrates strong returns on shareholder capital.
  • Strong capital position (+3% to +6%)
    • Healthy capital supports continued dividends, share repurchases, and resilience during economic downturns.
  • Stable credit quality (+2% to +5%)
    • No evidence of broad-based deterioration in the loan portfolio.

Weaknesses

  • Interest-rate sensitivity (-6% to -10%)
    • Future earnings remain influenced by changes in interest rates and deposit pricing.
  • Cyclical capital markets businesses (-4% to -8%)
    • Trading and investment banking revenues naturally fluctuate with market conditions.
  • Moderate long-term growth profile (-3% to -6%)
    • As a mature banking franchise, growth is expected to remain steady rather than rapid.

Opportunities

  • Continued investment banking recovery (+5% to +9%)
    • Improved corporate activity could further expand fee income.
  • Digital banking and AI productivity (+4% to +7%)
    • Ongoing technology investments should improve efficiency while strengthening customer relationships.
  • Higher shareholder returns (+3% to +6%)
    • Strong capital generation creates additional flexibility for dividends and share repurchases.

Threats

  • Economic slowdown and higher credit losses (-8% to -15%)
    • A recession would reduce loan demand while increasing credit costs.
  • Margin compression from lower interest rates (-6% to -10%)
    • Lower net interest income would reduce recurring earnings.
  • Regulatory changes (-3% to -7%)
    • Higher capital requirements could reduce future returns on equity.

Valuation Scenarios

Although Q2 demonstrated strong operating momentum, valuation should reflect both the quality of the franchise and the cyclical nature of banking. Rather than assuming today’s earnings represent either a permanent peak or a temporary anomaly, we evaluate three possible scenarios.

Bear Case — $52 (25%)

Assumes weaker net interest income, softer capital markets activity, modestly higher credit costs, and a lower valuation multiple.

Base Case — $64 (50%)

Assumes stable net interest income, healthy credit quality, continued profitability, and valuation multiples consistent with historical norms.

Bull Case — $74 (25%)

Assumes sustained earnings growth, continued strength across multiple business segments, accelerating shareholder returns, and modest valuation expansion.

Probability-Weighted Fair Value

Combining these scenarios produces a probability-weighted fair value of approximately $64 per share.


Verdict

Bank of America continues to demonstrate why it remains one of the highest-quality banking franchises in the United States. Its diversified earnings base, strong deposit franchise, disciplined capital allocation, and healthy balance sheet provide resilience across different economic environments.

Importantly, this conclusion is based primarily on the company’s official financial disclosures rather than market narratives or analyst opinions.

Following the earnings release, the market initially responded cautiously before the shares recovered later in the trading session. Our independent assessment suggests that investors ultimately recognized the quality of the quarter while continuing to evaluate the sustainability of future earnings.

At current prices, Bank of America appears modestly undervalued relative to our estimated intrinsic value of approximately $64 per share. While the valuation is attractive for long-term investors, it does not yet provide the wide margin of safety typically associated with a “fat pitch.”


Call to Action

Did you reach the same conclusion after reading Bank of America’s earnings report?

Do you believe the market is correctly valuing the company’s long-term earnings power, or is there still upside that investors have yet to recognize?

Share your thoughts in the comments, and follow SWOTstock for independent earnings analysis based on official company disclosures rather than market consensus.


Disclaimer

This article is intended for educational and informational purposes only and should not be considered financial advice or a recommendation to buy or sell any security. The analysis is based primarily on Bank of America’s official financial disclosures and management commentary, supplemented by independent valuation reasoning. Investors should conduct their own research and consider their individual financial circumstances before making investment decisions.


Bank of America Q1 2026 Earnings: Strong Quarter, But Is the Upside Already Priced In?

TL;DR Summary

Bank of America (BAC:NYSE) delivered a strong Q1 2026, with solid growth in net interest income, a rebound in investment banking, and stable credit quality. The market reacted positively, but not aggressively—because the key question hasn’t changed:

Is BAC a stable compounder deserving a higher multiple, or still a rate-sensitive cyclical bank?

Our probability-weighted valuation lands at ~$54, suggesting the stock is fairly valued today, with upside dependent on capital markets recovery and downside tied to credit normalization.


Quarter Recap

Bank of America opened 2026 with a quarter that looked stronger than many investors expected. Revenue reached $30.3 billion, up 7% year-over-year, while net income came in at $8.6 billion, translating into $1.11 EPS.

What stands out is not just the headline numbers, but the composition. Net interest income grew to $15.7 billion, signaling that the bank is still extracting value from its deposit base even in a maturing rate cycle. At the same time, capital markets activity showed clear signs of recovery, with investment banking fees and trading revenue both moving higher.

Underneath, credit quality remains controlled. Net charge-offs are still relatively low at 0.48% of loans, and capital remains strong with a CET1 ratio of 11.2%.

This is not a one-dimensional quarter—it’s a balanced earnings engine at work.


Key Highlights

The quarter tells a simple story: Bank of America is no longer relying on just one lever.

Net interest income continues to provide a stable base, while capital markets are beginning to add cyclical upside. Consumer banking and wealth management remain steady contributors, and the balance sheet continues to expand with loan growth holding firm.

At the same time, nothing in the quarter suggests excessive risk-taking. Credit remains benign, and capital levels leave room for continued shareholder returns.

That combination—growth without visible stress—is exactly what investors look for in a large-cap bank.


SWOT Analysis (with price impact ranges)

The real debate for Bank of America is not whether the business is performing—it clearly is. The question is how much of that performance is sustainable, and how the market should value it.

Strengths

Bank of America’s biggest strength today is the resilience of its earnings engine. Net interest income continues to grow despite concerns around peak rates, which suggests that its deposit franchise remains a structural advantage.

At the same time, the bank benefits from a highly diversified model. Consumer banking, wealth management, trading, and investment banking all contributed meaningfully in the quarter, reducing reliance on any single driver.

Finally, capital and credit remain solid. With a CET1 ratio above 11% and low charge-offs, the bank has both downside protection and flexibility to return capital.

Estimated price impact:
+3% to +10% across key strength drivers


Weaknesses

The core weakness is one that has always defined Bank of America: its sensitivity to interest rates. While that worked in its favor during rate hikes, it becomes a constraint if rates move lower more quickly than expected.

In addition, the bank’s scale creates structural inefficiencies. Large universal banks face higher fixed costs—technology, compliance, and operations—which limits operating leverage compared to smaller or more focused peers.

Estimated price impact:
-3% to -8%


Opportunities

The biggest opportunity lies in capital markets. The rebound in investment banking and trading activity in Q1 may be the early stages of a broader recovery cycle. If deal activity continues to improve, this could provide a meaningful boost to earnings beyond what is currently priced in.

At the same time, steady loan growth and a stable deposit base create a foundation for organic expansion without taking on excessive risk.

Estimated price impact:
+4% to +12%


Threats

The main risks are cyclical. Credit costs are currently low, but they are unlikely to stay there indefinitely. A normalization cycle could quickly pressure earnings if provisions rise faster than expected.

Macro uncertainty also remains a key factor. A combination of rate cuts and economic slowdown would hit both net interest income and loan growth at the same time.

Estimated price impact:
-5% to -12%

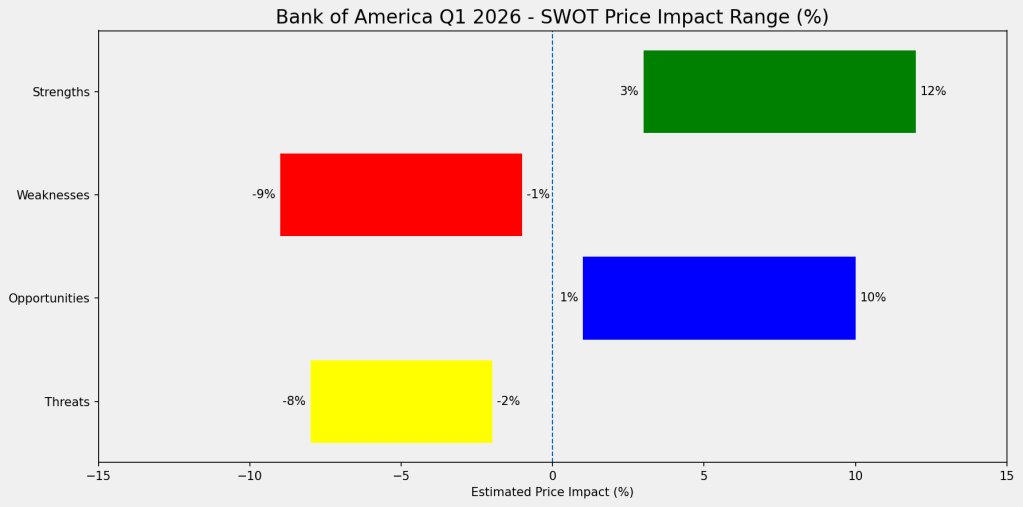
Bank of America Q1 2026 SWOT price impact chart showing strengths (+3% to +12%), weaknesses (-9% to -1%), opportunities (+1% to +10%), and threats (-8% to -2%) on a horizontal axis from -20% to +20%.
Bank of America’s valuation profile reflects balanced upside from capital markets and NII resilience, offset by downside risks from credit normalization and macro uncertainty.

Valuation Scenarios

The valuation comes down to how the market interprets this mix of strengths and risks.

Base Case (50%) — Stable but not re-rated

In the most likely scenario, Bank of America continues to deliver steady earnings with moderate growth. Net interest income stabilizes, capital markets gradually recover, and credit costs rise slightly but remain manageable.

Fair value: $52–$60


Bull Case (25%) — Earnings upgrades + multiple expansion

In a more optimistic scenario, capital markets rebound strongly and credit remains benign. The market begins to see Bank of America as a high-quality compounder rather than a cyclical bank, leading to both earnings upgrades and multiple expansion.

Fair value: $64–$75


Bear Case (25%) — Macro and credit pressure

In the downside scenario, rates fall faster than expected while credit costs rise. Earnings decline and the market applies a lower multiple, reflecting increased uncertainty.

Fair value: $32–$40


Probability-Weighted Valuation

Bringing these scenarios together results in a weighted fair value of approximately:

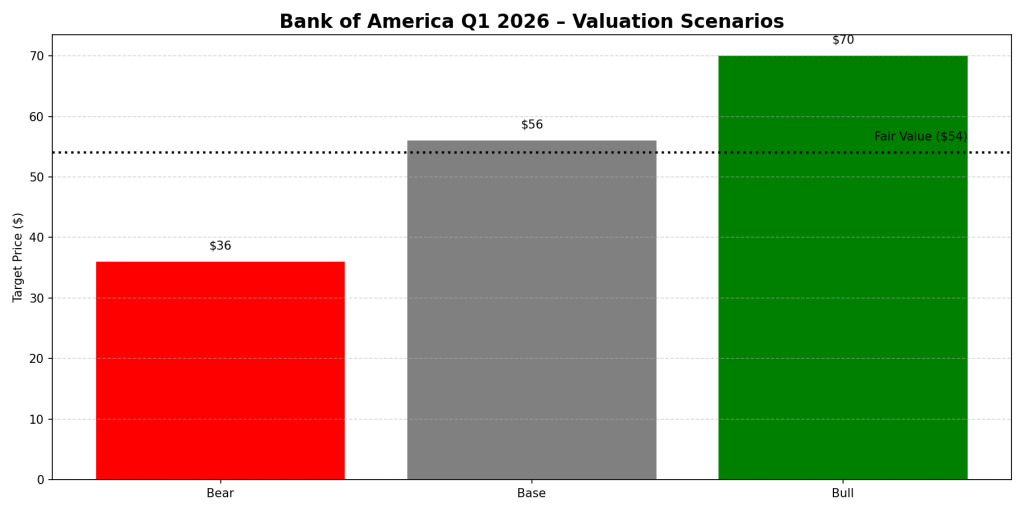
~$54 per share

At current levels, this suggests the stock is fairly valued, with limited margin of safety.

Bar chart showing Bank of America Q1 2026 valuation scenarios with bear case at $36, base case at $56, and bull case at $70, with a dotted fair value line at approximately $54.
Bank of America’s Q1 2026 valuation scenarios highlight a balanced risk-reward profile, with the current price near fair value, upside driven by capital markets recovery, and downside risk from credit normalization and macro uncertainty.

Verdict

Bank of America is executing well. The business is strong, diversified, and supported by solid capital and credit fundamentals.

But the stock is no longer cheap. The market is already pricing in a stable base case, leaving investors dependent on either a capital markets-driven upside surprise or exposed to a credit or macro-driven downside.

For value-oriented investors, this becomes a question of timing rather than conviction.


Call to Action

Would you buy Bank of America at $55, or wait for a better entry point closer to the downside scenario?

Let me know how you’re thinking about large-cap banks in this cycle.


Disclaimer

This analysis is for informational purposes only and does not constitute investment advice. All assumptions are based on Bank of America’s official earnings release and investor materials for Q1 2026. Investors should conduct their own research before making investment decisions.