🔋 AMD Q3 2025 — AI Growth Kicks Into High Gear, but Valuation Catches Up

AMD reported record Q3 2025 earnings with a 36% revenue increase to $9.25 billion and a gross margin of 54%. Data Center sales grew 22%, while Client & Gaming surged 73%. Despite strong results, stock dipped due to export-control concerns. Q4 revenue guidance is between $9.3-$9.9 billion.

🧭 TL;DR Summary

Advanced Micro Devices (AMD:NASDAQ) posted record Q3 2025 results: revenue up 36 % y/y to $ 9.25 billion, non-GAAP EPS $ 1.20, and gross margin 54 %.
Data Center sales jumped 22 %, Client & Gaming soared 73 %, while Embedded declined 8 %.
Guidance for Q4 calls for $ 9.3 – 9.9 billion revenue—yet the stock dipped ≈ 4 % after hours as investors digested export-control headwinds and lofty expectations.


🧾 Quarter Recap

AMD’s Q3 marked a clear inflection in its AI and compute franchise.
CEO Lisa Su described the quarter as “a step-up in our growth trajectory as our rapidly scaling data-center AI business drives significant revenue and earnings growth.”
Gross margin improved two points y/y to 52 % (GAAP) and 54 % (non-GAAP), underscoring richer product mix led by EPYC CPUs and Instinct GPUs.
Operating income more than doubled to $ 1.27 billion.

Segment breakdown:

  • Data Center: $ 4.34 b (+ 22 %) — 5th Gen EPYC and Instinct MI350 ramp.
  • Client + Gaming: $ 4.05 b (+ 73 %) — Ryzen and console demand rebound.
  • Embedded: $ 0.86 b (– 8 %) — soft industrial & networking orders.

Management guided Q4 revenue $ 9.3 – 9.9 b (midpoint $ 9.6 b), excluding China-bound MI308 GPU shipments awaiting approval.


🌟 Key Highlights

  1. AI acceleration: Instinct MI350 shipments ramping, with MI308 awaiting export clearance.
  2. Margin expansion: Gross margin 54 % shows strong mix shift to high-end compute.
  3. Balanced growth: Client & Gaming offset softer Embedded demand.
  4. Cautious guidance: China restrictions = headwind, but secular AI TAM tailwinds intact.

🧩 SWOT Analysis (with Price-Impact Ranges)

Strengths (+ 7 – 15 %)
High-margin AI and server products drive sustainable earnings growth. Data Center + Client momentum supports multiple expansion.

Weaknesses (– 6 – 12 %)
Exposure to export controls and volatile PC cycle; Embedded softness limits diversification.

Opportunities (+ 10 – 22 %)
Next-gen MI350 and Zen 5 launches could unlock share gains vs NVIDIA and Intel; AI server TAM expands through 2026.

Threats (– 8 – 18 %)
Regulatory uncertainty (China exports), intense AI competition, macro slowdown risk.

AMD Q3 2025 SWOT price impact chart showing strengths, weaknesses, opportunities, and threats with colored horizontal bars from –45 to +55 dollars, indicating potential stock price impact ranges.

💸 Valuation Scenarios

  • Bull Case (35 % probability)
    • 2026 E EPS ≈ $ 6.50
    • P/E multiple ≈ 40×
    • Target Price: $ 260 – 300 (+ 20 %)
    • Thesis: Strong AI GPU and EPYC share gains, China shipments resume, margin expansion continues.
  • Base Case (50 % probability)
    • 2026 E EPS ≈ $ 5.50
    • P/E multiple ≈ 35×
    • Target Price: $ 230 – 250 (± 0 %)
    • Thesis: Balanced growth across Data Center and Client, modest Embedded recovery, stable margins.
  • Bear Case (15 % probability)
    • 2026 E EPS ≈ $ 4.50
    • P/E multiple ≈ 30×
    • Target Price: $ 180 – 200 (– 20 %)
    • Thesis: AI spending slows, export restrictions persist, competition pressures gross margin.

🎯 Probability-weighted fair value: $ 242 – 255 per share — roughly aligned with current post-earnings price, indicating AMD is fairly valued with moderate upside if AI acceleration outperforms.💸 Valuation Scenarios
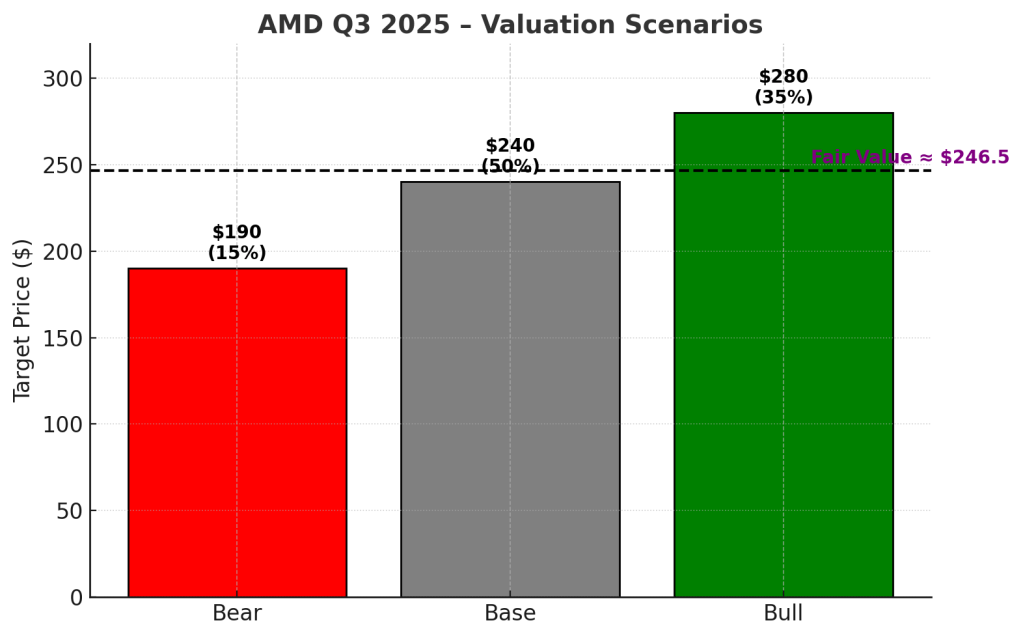
AMD Q3 2025 valuation scenarios chart showing Bear, Base, and Bull cases with target prices of $190, $240, and $280, and a dashed line marking fair value around $246.

🧠 Verdict

AMD Q3 2025 shows AI execution is translating into profits. The stock’s valuation now reflects that success.
Short-term pullbacks from export or competitive news could offer better entries, but long-term investors still have a clear AI compounder.

Call: ⚖️ Hold / Accumulate on Weakness
Fair Value: $ 242 – 255 per share


🗣️ Call to Action

If you’re an AI-infrastructure-focused investor, keep AMD on your watchlist for pullbacks below $ 240.
The next earnings cycle will reveal whether the MI350 and Zen 5 ramps translate into market-share inflection.


⚠️ Disclaimer

This analysis is based solely on AMD’s official Q3 2025 financial report and earnings call. It is not investment advice. Please conduct your own due diligence before making investment decisions.


AMD Q1 2025 Earnings Breakdown: AI Growth, Gaming Drag, and What Investors Need to Know

Discover AMD’s Q1 2025 earnings with a clear breakdown of AI growth, gaming challenges, and strategic risks. This analysis uses only official financial reports and earnings call data. Includes SWOT insights, valuation scenarios, and investor takeaways—all tailored for retail investors seeking actionable, trustworthy information.

Introduction: Why This Quarter Matters for AMD Investors

AMD just released its Q1 2025 results, and the numbers show a company in transformation. Strong momentum in data center and AI segments is powering growth, but challenges in gaming and macro-level headwinds are keeping the market cautious.

This article breaks down AMD’s earnings using only official sources: the company’s financial report and earnings call. We’ll walk through the financial details, strategic strengths and risks, and conclude with scenario-based valuations—all in a way that’s easy for retail investors to digest.


Quarterly Recap: Growth in Strategic Segments, Strategic Pressure in Legacy

In Q1 2025, AMD posted $5.5 billion in revenue, representing a 2% year-over-year increase. The standout performer was its Data Center segment, which grew 80% YoY, fueled by strong demand from cloud service providers for AI acceleration.

Most notably, AMD surpassed $1 billion in AI GPU revenue for the first time—a major milestone that reflects traction for its MI300 series. On the flip side, the Gaming segment recorded an $800 million inventory write-down, reflecting weaker-than-expected demand and a product transition gap.

Gross margin came in at 52%, down slightly due to the write-down, but operating efficiency remained solid. AMD reaffirmed its full-year $4.3B AI GPU sales target and outlined a clear product roadmap through 2026 with the upcoming MI325 and MI350 chips.


Q1 2025 Financial Highlights

  • Revenue: $5.5B (up 2% YoY)
  • AI GPU Revenue: Surpassed $1B
  • Data Center Growth: +80% YoY
  • Gross Margin: 52%
  • EPS: $0.77 (non-GAAP)
  • Inventory Write-Down: $800M in Gaming
  • FY25 Guidance: $4.3B in AI GPU sales
  • Roadmap: MI325 in mid-2025, MI350 in 2026
  • Geopolitical Exposure: Up to $1.5B at risk from export controls
Line chart showing AMD’s revenue, net income, and capital expenditures over the last five quarters through Q1 2025, highlighting growth in profitability.

Market Reaction and Sentiment

Following the earnings release, AMD’s stock traded slightly lower despite the beat on AI growth—why? Analysts and investors remain cautious due to:

  • Uncertainty around China export restrictions ($1.5B potential impact)
  • Softness in consumer-facing segments like Gaming and Embedded
  • Comparisons to NVIDIA, whose AI platform is more mature (especially on software)

Still, institutional sentiment remains bullish on AMD’s AI roadmap, with many analysts reiterating “Buy” ratings but adjusting near-term price targets for geopolitical risk.


SWOT Analysis: Strategic Positioning with Key Risks

Strengths:
AMD’s biggest strength this quarter is its breakthrough in the AI market. The MI300 series GPUs brought in over $1 billion in Q1 alone, with management reaffirming a $4.3 billion target for FY2025. This strong performance in the Data Center segment, which grew 80% year-over-year, positions AMD as a serious challenger to NVIDIA in AI infrastructure.

Estimated Stock Price Impact (Strengths):

  • AI GPU momentum: +12 per share
  • Data Center growth: +5 per share
  • Total Strength Impact: +$17/share

Weaknesses:
While AMD’s AI story is strong, not all segments are growing. The Gaming division recorded a significant $800 million inventory write-down, putting pressure on margins. Additionally, the mix shift toward high-R&D segments has led to narrower gross margins in the short term.

Estimated Stock Price Impact (Weaknesses):

  • Gaming inventory write-down: –4 per share
  • Margin compression: –3 per share
  • Total Weakness Impact: –$7/share

Opportunities:
Looking ahead, AMD has multiple growth levers. The planned release of the MI325 (2025) and MI350 (2026) promises to extend AI leadership. The company is also poised to gain CPU share in the enterprise segment, especially with new EPYC and Ryzen launches. The edge AI market—spanning automotive, industrial, and embedded systems—presents a long-term expansion opportunity.

Estimated Stock Price Impact (Opportunities):

  • Future AI product roadmap: +10 per share
  • Enterprise CPU growth: +4 per share
  • Total Opportunity Impact: +$14/share

Threats:
Geopolitical tension is AMD’s biggest external risk. The U.S. export restrictions on AI chips could put up to $1.5 billion in revenue at risk. A return of Trump-era tariffs and continued high interest rates could further weigh on valuation multiples.

Estimated Stock Price Impact (Threats):

  • China export risk: –7 per share
  • Tariff & macroeconomic drag: –10 per share
  • Total Threat Impact: –$17/share

SWOT Summary Table with Stock Price Impact

SWOTKey FactorImpact on Stock Price (USD)
StrengthsAI GPU sales momentum (MI300 series)+12
Data center revenue growth+5
Weaknesses$800M gaming inventory write-down–4
Gross margin pressure from product mix–3
OpportunitiesMI325 and MI350 AI roadmap+10
Enterprise CPU share gains+4
Threats$1.5B China export restrictions–7
Tariff risk and macro valuation pressure–10

Net SWOT Impact on Stock Price: +$7 per share

Horizontal bar chart illustrating estimated AMD stock price impact by SWOT category in Q1 2025, including strengths, weaknesses, opportunities, and threats.

Valuation Scenarios: What’s Priced In?

We constructed three valuation scenarios using a DCF-based and multiple-driven approach:

ScenarioTarget PriceAssumptionsProbability
Bull Case$135AI GPU revenue beats guide, China risk contained25%
Base Case$118.70AI guidance met, some weakness in Gaming persists60%
Bear Case$78Export controls expand, weak macro hits enterprise & gaming15%

Probability-weighted fair value: $110.13

Bar chart comparing AMD’s estimated stock price under bear, base, and bull case scenarios in Q1 2025.

Conclusion: Is AMD Fairly Valued?

At its current price of approximately $98, AMD appears undervalued by ~12% relative to our base-case scenario and ~21% compared to the fundamentals-only estimate (ignoring macro headwinds). However, when we factor in external risks like China exposure and interest rate volatility, the stock looks more fairly valued.

For investors with a 2-3 year horizon and confidence in AMD’s AI strategy, the current price offers an attractive risk-adjusted entry point. But short-term performance may remain choppy as macro risks play out.


Disclaimer

This content is for informational purposes only and should not be construed as financial or investment advice. The analysis presented in this article is based solely on publicly available information from AMD’s official Q1 2025 financial report and earnings call transcript. No third-party analyst opinions, speculative media commentary, or unofficial forecasts were included. All valuation scenarios, estimates, and statements are the author’s interpretation of the data and do not represent forward-looking guidance from AMD.

Please conduct your own due diligence or consult a licensed financial advisor before making any investment decisions.


Stay Ahead of the Market

If you found this breakdown helpful and want more clear, data-driven insights directly from earnings calls and official filings — subscribe to our newsletter. No noise, no hype — just signal.

👉 [Subscribe Now]


One response to “AMD Q1 2025 Earnings Breakdown: AI Growth, Gaming Drag, and What Investors Need to Know”

  1. NVIDIA Q1 FY2025: AI Boom Powers Revenue—but Is the Stock Already Fully Priced? – SWOT Stock – Smart Investing Made Simple Avatar

    […] check out our recent breakdowns of AMD Q1 2025, Palantir Q1 2025, Meta Q1 2025 and Alphabet Q1 2025 for more actionable […]

    Like

Leave a comment