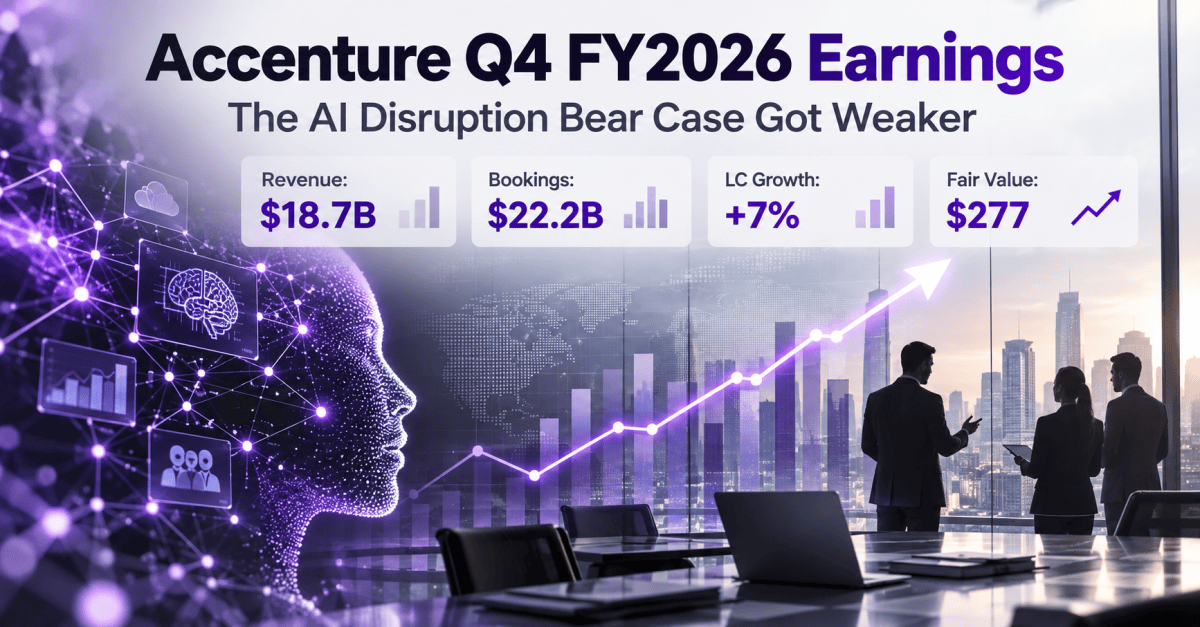
Accenture Q4 FY2026 Earnings: The AI Disruption Bear Case Just Got Weaker

Accenture’s Q4 FY2026 results show a strong recovery, with revenue reaching $18.7 billion, up 7%, and new bookings at $22.2 billion, up 5%. This improvement addresses concerns from Q3 about revenue growth and bookings decline. However, FY2027 growth guidance remains modest at 3%–6%, proposing cautious optimism for investors.

TL;DR Summary

Accenture’s (NYSE:ACN) Q4 FY2026 results materially improved the investment thesis after the severe selloff that followed Q3.

Revenue reached $18.7 billion, up 7% in local currency, while new bookings increased to $22.2 billion, up 5% in local currency. Full-year adjusted EPS increased 8% to $13.97, free cash flow reached $11.6 billion, and management expects another year of growth in FY2027.

The most important development is not simply that Accenture beat expectations. It is that the two numbers that caused the biggest concern last quarter — revenue growth and bookings — both improved sharply.

That weakens the argument that AI is already causing structural deterioration in Accenture’s consulting business.

However, investors should not jump to the opposite extreme. FY2027 revenue guidance remains only 3%–6%, meaning Accenture has not suddenly returned to high growth.

Our updated valuation therefore separates two ideas:

  • The business risk has fallen materially.
  • The stock still should not automatically regain its old premium valuation multiple.

Our updated probability-weighted fair value is approximately $277 per share.


Quarter Recap

Accenture ended FY2026 much more strongly than Q3 suggested.

Fourth-quarter revenue was $18.7 billion, increasing 6% in U.S. dollars and 7% in local currency.

That compares with only about 3% local-currency growth in Q3.

More importantly, growth was broad-based across Accenture’s geographic markets, industry groups, consulting operations and managed services. Management said revenue finished above the high end of its own quarterly guidance range.

New bookings were also substantially stronger.

Q4 bookings reached $22.2 billion, increasing 4% in U.S. dollars and 5% in local currency, producing a book-to-bill ratio of approximately 1.2.

This matters because bookings were one of the largest concerns after Q3.

In June, declining bookings created a plausible bearish argument:

Weak bookings could lead to weak future revenue, which could indicate that AI was beginning to reduce demand for traditional consulting services.

Q4 does not prove that this risk has disappeared.

But the numbers no longer support the simple assumption that bookings are entering a persistent downward trend.


Key Highlights

  • Q4 revenue reached $18.7 billion.
  • Revenue increased 7% in local currency.
  • Q4 new bookings reached $22.2 billion.
  • Bookings increased 5% in local currency.
  • Q4 book-to-bill was approximately 1.2.
  • Full-year FY2026 revenue reached $74.2 billion, up 5% in local currency.
  • Full-year adjusted EPS increased 8% to $13.97.
  • Full-year free cash flow reached $11.6 billion.
  • Adjusted operating margin increased to 15.8%.
  • Accenture returned a record $11.5 billion to shareholders during FY2026.
  • Management recorded a new high of 141 quarterly client bookings worth $100 million or more during the year.
  • FY2027 revenue growth guidance is 3%–6% in local currency.
  • FY2027 EPS guidance is $14.39–$14.81.
  • FY2027 free cash flow guidance is $11.0–$11.8 billion.

The results support a business that is still growing, still highly cash generative and still winning large enterprise transformation programs.

They do not support the idea that Accenture is already experiencing a collapse in demand caused by AI.


SWOT Analysis

Accenture’s Q4 results materially improve the balance between risk and opportunity.

The company still faces a genuine long-term question over whether AI will reduce the amount of human consulting work required by enterprise customers. But Q4 provides much stronger evidence that Accenture can continue capturing transformation spending while that technological transition develops.

Strengths

  • Revenue growth reaccelerated materially. Q4 local-currency revenue growth increased to 7%, well above the growth rate seen in Q3.
    • Estimated price impact: +8% to +15%
  • Bookings recovered strongly. New bookings increased to $22.2 billion and grew 5% in local currency.
    • Estimated price impact: +10% to +18%
  • Managed services provides recurring demand. Managed-services bookings reached approximately $12.8 billion and produced a stronger book-to-bill ratio than consulting.
    • Estimated price impact: +4% to +8%
  • Margins remain resilient. Adjusted FY2026 operating margin increased to 15.8%, and management expects another 10–30 basis points of expansion in FY2027.
    • Estimated price impact: +5% to +10%
  • Free cash flow remains a major strength. FY2026 free cash flow reached $11.6 billion.
    • Estimated price impact: +5% to +10%
  • Capital allocation remains shareholder-friendly. Accenture returned a record $11.5 billion to shareholders during FY2026.
    • Estimated price impact: +3% to +7%

Weaknesses

  • FY2027 growth expectations remain modest. Management expects only 3%–6% local-currency revenue growth.
    • Estimated price impact: -8% to -15%
  • Consulting demand has stabilized more clearly than it has accelerated. The quarter provides evidence of recovery, but not yet evidence of a new high-growth cycle.
    • Estimated price impact: -4% to -8%
  • Growth remains partly dependent on acquisitions and continued reinvestment.
    • Estimated price impact: -5% to -10%
  • Q4 free cash flow was lower than the prior-year quarter even though full-year cash generation remained very strong.
    • Estimated price impact: -2% to -5%

Opportunities

  • Enterprise AI transformation could become a multi-year growth driver. Large companies increasingly need help integrating models, data, security, governance and workflows rather than simply buying AI software.
    • Estimated price impact: +10% to +25%
  • Accenture could become an important orchestration layer between enterprises and AI platforms. Its existing customer relationships could become more valuable as companies attempt increasingly complex AI transformations.
    • Estimated price impact: +10% to +20%
  • Managed services may benefit from AI complexity. Businesses may increasingly outsource ongoing AI operations, governance and integration rather than manage everything internally.
    • Estimated price impact: +8% to +18%
  • Large transformation programs remain strong. Accenture reached a record 141 quarterly client bookings above $100 million during FY2026.
    • Estimated price impact: +8% to +15%

Threats

  • AI could still reduce demand for labor-intensive consulting work. Generative AI can potentially reduce coding, analysis, implementation and support hours.
    • Estimated price impact: -12% to -25%
  • Productivity gains could eventually pressure billing economics. Even if Accenture retains customers, fewer human hours may be required to deliver equivalent outcomes.
    • Estimated price impact: -8% to -18%
  • Acquisition-supported growth could mask weaker organic growth.
    • Estimated price impact: -5% to -12%
  • Higher bond yields could limit valuation expansion. A company growing revenue at 3%–6% is more vulnerable to multiple compression when discount rates rise.
    • Estimated price impact: -10% to -20%

Valuation Scenarios

The Q4 results improve our view of Accenture’s business durability, but they do not justify immediately restoring the company’s historical premium valuation.

Management’s FY2027 EPS guidance of $14.39–$14.81 provides a useful anchor for the valuation.

We use approximately $14.60 as normalized FY2027 earnings power.

Bear Scenario — $219

The bear case assumes Accenture remains a strong company but becomes permanently valued as a mature, slow-growing professional services business.

Assumptions:

  • Revenue growth approaches the bottom of management’s 3%–6% guidance.
  • Consulting bookings weaken again.
  • AI increases productivity but reduces billable labor requirements.
  • Enterprise spending remains cautious.
  • Higher interest rates prevent valuation expansion.

Calculation:

  • FY2027 EPS: approximately $14.60
  • Valuation multiple: 15x
  • Estimated value: $219

Probability:

25%

This scenario no longer assumes the business is breaking.

Instead, it assumes that Accenture survives the AI transition successfully but investors no longer award it a premium growth multiple.


Base Scenario — $277

The base case assumes Q4 represents stabilization rather than a temporary rebound.

Assumptions:

  • Revenue growth settles around 4%–5%.
  • Bookings remain healthy.
  • Managed services provide recurring demand.
  • AI transformation projects replace enough traditional consulting work to prevent structural revenue deterioration.
  • Margins continue expanding modestly.
  • Accenture retains a moderate quality premium.

Calculation:

  • FY2027 EPS: approximately $14.60
  • Valuation multiple: 19x
  • Estimated value: $277

Probability:

50%

This scenario best reflects the evidence available today.


Bull Scenario — $336

The bull case assumes Accenture proves that AI is a net expansion opportunity rather than merely a defense against disruption.

Assumptions:

  • Revenue reaches or exceeds the upper end of FY2027 guidance.
  • Bookings remain consistently strong.
  • AI transformation programs expand significantly.
  • Managed services grow alongside AI adoption.
  • Organic growth becomes increasingly visible.
  • Investors begin treating Accenture as a durable compounder again.

Calculation:

  • FY2027 EPS: approximately $14.60
  • Valuation multiple: 23x
  • Estimated value: $336

Probability:

25%

A higher multiple would require stronger evidence of sustained growth rather than one strong quarter.


Probability-Weighted Fair Value

  • Bear case: $219 × 25% = $54.75
  • Base case: $277 × 50% = $138.50
  • Bull case: $336 × 25% = $84.00

Probability-weighted fair value: approximately $277 per share

Our fair-value range is therefore approximately:

$219–$336

with a central estimate of:

$277

The current post-earnings trading level around the low-$200s remains below this estimate, even after the sharp earnings-day rally.


Verdict

The most important conclusion from Accenture’s Q4 earnings is not that the company has suddenly become a high-growth AI stock.

It is that the evidence for the most aggressive AI-disruption bear case has weakened.

Three months ago, investors had several legitimate concerns:

  • bookings were falling,
  • local-currency revenue growth had slowed to around 3%,
  • full-year guidance had been reduced,
  • and investors increasingly feared that AI could reduce demand for traditional consulting work.

Q4 produced a very different set of numbers.

Bookings grew.

Revenue growth accelerated.

Margins held up.

Free cash flow remained substantial.

Management is guiding for continued growth in FY2027.

That does not eliminate the AI disruption question.

AI can simultaneously create billions of dollars of transformation work for Accenture while reducing the amount of labor required to perform traditional consulting services. Both forces can exist at the same time.

The investment question is therefore no longer simply:

“Will AI destroy consulting?”

A more useful question is:

“Can Accenture capture enough value from enterprise AI transformation to offset the productivity that AI removes from its traditional labor-based business?”

Q4 moves the evidence toward yes, but it does not prove the case yet.

For a Type 2 DIY value investor, that distinction matters.

The business now appears substantially less impaired than the market feared after Q3, while the current valuation still reflects significant uncertainty about Accenture’s long-term AI economics.

Our updated central fair value is approximately $277 per share.


Call to Action

Accenture’s earnings raise an important question for long-term investors:

Will AI ultimately reduce the value of traditional consulting, or will enterprise AI become an even larger transformation opportunity for firms such as Accenture?

Follow SWOTstock as we track Accenture’s bookings, organic growth, margins and AI economics over the coming quarters to see which thesis the financial evidence ultimately supports.


Disclaimer

This article is for informational and educational purposes only and does not constitute investment advice or a recommendation to buy or sell any security.

All valuation estimates involve assumptions regarding future earnings, growth, business performance and valuation multiples. Actual results may differ materially.

Investors should perform their own research and consider their financial circumstances, objectives and risk tolerance before making investment decisions.
Accenture Q2 FY2026 Earnings: Strong AI Demand, But Still Waiting for Growth Acceleration

Accenture reported solid Q2 FY2026 results with record bookings of $22.1 billion and raised its revenue growth guidance to 4–7%. However, revenue growth remains mid-single digits, and GAAP margins compressed. The stock price is near its fair value, with future performance dependent on executing AI strategies rather than just demand narratives.

TL;DR Summary

Accenture (ACN:NYSE) delivered a solid quarter with record bookings and raised guidance, confirming strong enterprise AI demand. However, revenue growth remains in the mid-single digits, and margin pressure suggests AI investments are still in the build phase. The stock is trading close to its probability-weighted fair value, meaning future upside depends on execution—not narrative.


Quarter Recap

Accenture reported Q2 FY2026 results that reflect strong execution but measured growth. Revenue reached $18.0 billion, growing 7% in U.S. dollars and 4% in local currency. Adjusted EPS came in at $3.59, up 10% year over year, while GAAP EPS declined 4%.

The most notable metric was bookings, which hit a record $22.1 billion for a second quarter, indicating strong forward demand. The company also raised its full-year revenue growth guidance to 4–7%, reinforcing confidence in its pipeline.

However, margin trends were mixed. Adjusted operating margin improved slightly, but GAAP margins declined, reflecting continued investment in AI capabilities.


Key Highlights

  • Revenue: $18.0B (+7% USD, +4% local currency)
  • Adjusted EPS: $3.59 (+10% YoY)
  • GAAP EPS: $3.19 (-4% YoY)
  • Record bookings: $22.1B
  • Raised FY2026 revenue growth guidance: 4–7%
  • Free cash flow: $2.68B
  • Share repurchases: $1.7B

SWOT Analysis

Accenture’s results reinforce its position as a high-quality execution platform for enterprise transformation and AI adoption. The company is seeing strong demand and improving visibility, but the market is still waiting for clear evidence that this demand can translate into sustained revenue acceleration and margin expansion.


Strengths

  • Record bookings ($22.1B) → strong forward revenue visibilityEstimated impact: +6% to +10%
  • Raised FY2026 guidance (4–7%) → improving confidenceEstimated impact: +4% to +7%
  • Balanced model (Consulting + Managed Services)Estimated impact: +3% to +6%
  • Positioned as enterprise AI orchestrator across ecosystemsEstimated impact: +5% to +12% (long-term)

Weaknesses

  • Revenue growth still mid-single digit (4% local currency)Estimated impact: -5% to -10%
  • GAAP margin compression (-70bps)Estimated impact: -3% to -6%
  • GAAP EPS decline (-4% YoY)Estimated impact: -3% to -5%

Opportunities

  • AI bookings converting into revenue accelerationEstimated impact: +10% to +20%
  • Early-stage enterprise AI adoption cycleEstimated impact: +8% to +15%
  • Large deal momentum (41 clients >$100M bookings)Estimated impact: +5% to +10%

Threats

  • AI commoditization (clients internalizing capabilities)Estimated impact: -8% to -15%
  • Hyperscalers capturing more value chainEstimated impact: -5% to -12%
  • Macro-driven IT spending volatilityEstimated impact: -6% to -10%
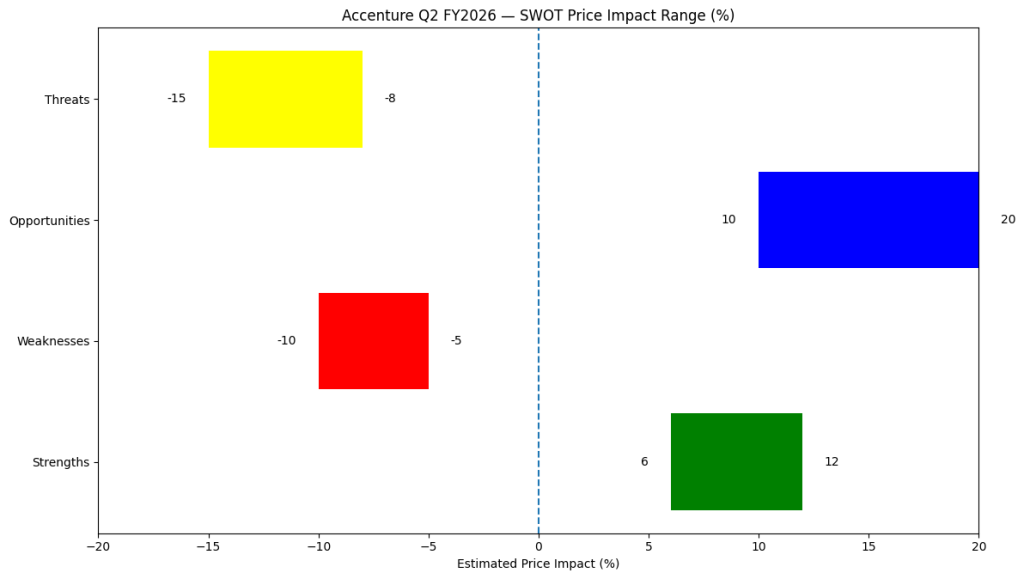
Horizontal SWOT chart showing Accenture Q2 FY2026 estimated stock price impact ranges, with strengths and opportunities in positive territory and weaknesses and threats in negative ranges on a -20% to +20% scale.
SWOT price impact ranges for Accenture’s Q2 FY2026 earnings, highlighting the balance between strong AI-driven demand and ongoing growth and margin constraints.

Valuation Scenarios

Accenture is currently being valued as a stable, high-quality operator with AI exposure, but not yet as a high-growth AI beneficiary. The key variable remains whether strong bookings can translate into sustained revenue acceleration.


Bear Case — $170 to $180

If revenue growth remains around 4–5% and AI demand takes longer to convert into revenue, while margins remain under pressure, the stock could see multiple compression toward traditional consulting peers.


Base Case — $195 to $210

If Accenture delivers within its updated 4–7% growth guidance and AI contributes incrementally without significantly accelerating growth, the stock is likely to remain around current levels with modest upside.


Bull Case — $230 to $260

If AI bookings translate into revenue acceleration above 8–10% and margins expand through operating leverage, Accenture could be re-rated as a leading AI execution platform.


Probability-weighted fair value

Based on the scenario analysis:

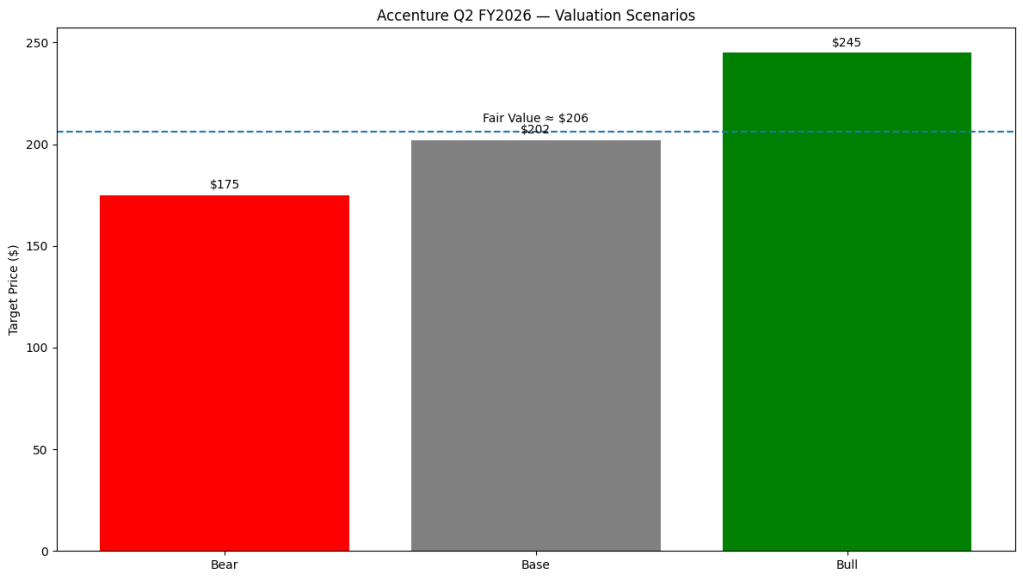
  • Bear case (25%): ~$175
  • Base case (50%): ~$202
  • Bull case (25%): ~$245

👉 Estimated fair value: ~$206

At a current price of around $203, Accenture is trading very close to its probability-weighted fair value, suggesting that the market is already pricing in its current level of execution.

Bar chart showing Accenture Q2 FY2026 valuation scenarios with bear case at $175, base case at $202, and bull case at $245, including a dashed fair value line at approximately $206.
Accenture Q2 FY2026 valuation scenarios showing bear, base, and bull price targets, with a probability-weighted fair value of approximately $206 based on execution and AI growth assumptions.

Verdict

Accenture continues to execute well, supported by strong demand and improving guidance. However, the market is still waiting for clear evidence that AI demand can drive sustained revenue acceleration.

At current levels, the stock appears fairly valued. This shifts the investment case from valuation-driven upside to execution-driven upside.

For now, Accenture remains a “show-me” story—a high-quality compounder with AI optionality, but not yet a full AI re-rating.


Call to Action

If you want more breakdowns like this—focused on how earnings translate into real price impact—follow SWOTstock for SWOT analysis on major companies.


Disclaimer

This analysis is for informational purposes only and does not constitute financial advice. Always conduct your own research before making investment decisions.


Accenture Q1 FY2026 Earnings: A Wonderful Business, Still Waiting for Growth

Accenture reported strong fiscal Q1 2026 results, exceeding revenue and earnings expectations while managing margins and generating cash. However, growth remains cautious with low-single-digit revenue increases. AI demand is emphasized as crucial for long-term growth, yet short-term challenges persist. The stock is viewed as fairly valued at approximately $270.

TL;DR

Accenture  (ACN:NYSE) delivered another quarter of solid execution, beating expectations on revenue and earnings while maintaining margins and strong cash generation. AI demand continues to build, but management remains cautious on near-term revenue acceleration. At around $270, ACN appears fairly valued, with upside dependent on whether AI-led reinvention can meaningfully lift topline growth.


Quarter Recap

  • Fiscal Q1 2026 revenue came in at the high end of guidance, reflecting resilient enterprise demand despite a cautious macro environment.
  • Adjusted earnings grew faster than revenue, supported by disciplined cost control and modest operating leverage.
  • New bookings remained healthy, including continued momentum in AI-related transformation programs.
  • Management reiterated a cautious full-year outlook, emphasizing execution and long-term positioning rather than near-term acceleration.

Key Highlights

  • Revenue growth remained in the low- to mid-single-digit range, consistent with guidance.
  • Adjusted operating margins expanded modestly year over year.
  • Free cash flow supported ongoing dividends and share repurchases.
  • AI was framed as a core component of multi-year reinvention programs, not a standalone growth spike.
  • U.S. federal-related work continued to weigh on near-term growth visibility.

SWOT Analysis

Accenture’s investment profile reflects a balance between durable execution strength and a growth trajectory that remains steady rather than accelerating. The ranges below translate qualitative factors into estimated stock price impact.

Strengths

  • Deep enterprise relationships and recurring transformation demand (+8% to +12%)
  • AI embedded into large-scale reinvention programs, supporting long-term monetization (+6% to +10%)
  • Strong cash flow, balance sheet discipline, and shareholder returns (+4% to +6%)

Strengths — overall impact: +18% to +28%


Weaknesses

  • Low-single-digit organic revenue growth profile (–6% to –10%)
  • Continued softness in U.S. federal business (–4% to –7%)
  • Premium valuation leaves limited margin for disappointment (–5% to –8%)

Weaknesses — overall impact: –15% to –25%


Opportunities

  • Scaling AI-led reinvention programs across global enterprises (+10% to +18%)
  • Operating leverage if demand gradually normalizes (+6% to +10%)
  • Leadership role as an enterprise AI orchestrator across platforms and models (+5% to +8%)

Opportunities — overall impact: +21% to +36%


Threats

  • Prolonged enterprise budget caution delaying large transformation decisions (–10% to –15%)
  • Investor narrative around AI commoditization compressing consulting multiples (–8% to –12%)
  • Competitive pricing pressure from smaller firms and in-house teams (–5% to –8%)

Threats — overall impact: –23% to –35%

Accenture Q1 FY2026 SWOT price impact chart showing estimated stock impact ranges: strengths +18% to +28%, weaknesses −15% to −25%, opportunities +21% to +36%, and threats −23% to −35%, with a dashed zero reference line.

Valuation Scenarios

Accenture’s valuation outcome hinges less on margin execution—which remains strong—and more on whether AI-driven reinvention can re-accelerate revenue growth.

Using $270 as the current price anchor:

Bear Case

  • Revenue growth remains around 2–3%
  • Federal weakness persists and AI monetization is slower than expected
  • Valuation multiple compresses toward the lower end of historical ranges
  • Implied price: ~$209 (–22.5%)

Base Case

  • Revenue growth stabilizes around 4–5%
  • AI bookings convert gradually into revenue
  • Margins expand modestly, supporting high-single-digit EPS growth
  • Implied price: ~$290 (+7.5%)

Bull Case

  • AI-led reinvention drives sustained revenue acceleration above 6%
  • Enterprise spending cycle improves
  • Operating leverage supports double-digit EPS growth with modest multiple expansion
  • Implied price: ~$351 (+30%)

Fair Value Assessment

Applying a probability-weighted approach:

  • Bear: 25%
  • Base: 50%
  • Bull: 25%

This results in a probability-weighted fair value of approximately $285, or about 5–6% upside from current levels.

Accenture valuation scenarios chart based on Q1 FY2026 earnings, showing bear case price target of $209, base case $290, bull case $351, and a probability-weighted fair value of $285.

Verdict

Accenture remains a high-quality compounder with durable client relationships, strong execution, and disciplined capital returns. At around $270, the stock looks fairly valued rather than cheap. Downside is cushioned by cash flow and margins, but meaningful upside will require clearer evidence that AI-led reinvention can translate into sustained topline acceleration.


Call to Action

If you’re tracking enterprise AI adoption beyond the hype, follow SWOTstock for earnings-driven analysis that focuses on what actually moves stock prices.


Disclaimer

This article is for informational purposes only and does not constitute investment advice. All analysis is based on publicly available, official company disclosures and earnings call commentary. Investors should conduct their own research or consult a financial professional before making investment decisions.