Goldman Sachs Q2 2026: Record Earnings, but Is a 23% ROE Already Priced In?

Goldman Sachs reported remarkable Q2 results, with net revenue up 39% to $20.34 billion and EPS rising 92% to $20.98. While strong across various sectors, the current valuation appears high at $1,152.07, trading at 3.13 times book value. The fair value estimate is around $920, reflecting limited investment safety.

TL;DR Summary

Goldman Sachs (NYSE:GS) delivered an exceptional second quarter. Net revenue rose 39% to a record $20.34 billion, EPS increased 92% to $20.98, and annualized return on equity reached 23.5%. The strength extended across investment banking, FICC, Equities and Asset & Wealth Management, while operating leverage and capital returns also improved.

The market responded decisively. Goldman shares advanced 9.0% on the earnings day, from $1,045.91 to $1,140, and closed the following session at $1,152.07.

The business momentum is real, but valuation is the central issue. At $1,152.07, Goldman trades at approximately 3.13 times book value and 3.42 times tangible book value. Our probability-weighted fair value is approximately $920. The current price effectively requires Goldman to sustain an ROE close to 23%—almost equal to the exceptional Q2 result.

  • SWOTstock fair value: approximately $920
  • Reasonable fair-value range: $850–$950
  • Bear scenario: $505
  • Base scenario: $860
  • Bull scenario: $1,390
  • Verdict: Excellent operating performance, but limited margin of safety at the post-earnings price

Quarter Recap

Goldman Sachs reported net revenue of $20.34 billion and net earnings of $6.63 billion for the quarter ended June 30, 2026. Diluted EPS reached $20.98, compared with $10.91 a year earlier and $17.55 in the first quarter.

Profitability improved substantially. Annualized ROE reached 23.5%, annualized ROTE reached 25.5%, and the efficiency ratio improved to 57.4%. Revenue grew faster than expenses, producing a 73% increase in pre-tax earnings.

The market reaction reflected the scale of that improvement. Goldman closed at $1,045.91 before the release and $1,140 afterward, a gain of 9.0%. This article does not use analyst estimates or news commentary to explain the move. The interpretation is based on Goldman’s official results: earnings increased sharply, the improvement was broad, and several indicators pointed to continued activity beyond the quarter.

The important question for investors is no longer whether Q2 was strong. It is whether the quarter represents a new sustainable level of profitability or a particularly favorable point in the capital-markets cycle.

Key Highlights

Goldman’s results were led by Global Banking & Markets, but the strength was not limited to one business.

  • Global Banking & Markets revenue increased 53% to $15.52 billion. The segment produced pre-tax earnings of $7.50 billion and a 27.5% ROE.
  • Investment-banking fees increased 55% to $3.40 billion. Equity underwriting rose 130%, debt underwriting rose 75%, and the investment-banking backlog increased sequentially.
  • FICC revenue increased 32% to $4.59 billion. Financing revenue reached a record, supported by mortgages and structured lending.
  • Equities revenue increased 72% to a record $7.42 billion. Both intermediation and financing reached record levels.
  • Asset & Wealth Management revenue increased 20% to $4.60 billion. Management and other fees reached a record $3.36 billion.
  • Assets under supervision reached a record $4.04 trillion. Goldman recorded $230 billion of total net inflows and its 34th consecutive quarter of long-term fee-based inflows.
  • Alternative-investment fundraising reached a quarterly record of $59 billion. Alternative assets under supervision increased to $459 billion.
  • Operating expenses increased 26% to $11.67 billion. Although substantial, this remained below the 39% increase in revenue.
  • Credit-loss provisions declined to $102 million. This supported earnings but should not automatically be treated as a permanent run rate.
  • Goldman returned $5.36 billion to common shareholders. The company repurchased $4.00 billion of shares and increased its quarterly dividend by 11% to $5.00.
  • Book value reached $367.67 per share. Tangible book value was $336.61 per share.

SWOT Analysis

Goldman’s strengths are visible in its franchise breadth, operating leverage and expanding recurring fee base. Its weaknesses are concentrated in the cyclicality of the record results and the premium valuation now assigned to them. The estimated price impacts below describe the potential one-year effect if each factor becomes the dominant incremental driver. They should not be added together because several factors overlap.

Strengths

  • Exceptional profitability and operating leverage: estimated impact +6% to +12%. Q2 ROE reached 23.5%, while revenue growth outpaced expense growth by 13 percentage points.
  • Broad strength across the core franchise: estimated impact +5% to +10%. Investment banking, FICC, Equities and Asset & Wealth Management all expanded.
  • Growing recurring fee base: estimated impact +4% to +8%. Record assets under supervision and 34 consecutive quarters of long-term fee-based inflows improve revenue durability.
  • Strong capital and liquidity: estimated impact +2% to +5%. The standardized CET1 ratio increased to 12.9%, average global core liquid assets reached $555 billion, and the dividend increased.

Weaknesses

  • Dependence on an exceptional Equities quarter: estimated impact −10% to −18%. Equities generated approximately 36% of firmwide revenue and grew 72%.
  • Demanding price-to-book valuation: estimated impact −15% to −30%. The stock trades above three times book value, leaving limited protection if ROE returns to the mid-teens.
  • Limited tangible-book accumulation: estimated impact −3% to −7%. Tangible book value increased only $0.33 sequentially despite $20.98 of EPS, partly because of substantial capital distributions.
  • Residual Platform Solutions weakness: estimated impact −2% to −5%. Revenue declined 64%, and the segment recorded a $48 million pre-tax loss.
  • Pressure on private-banking margins: estimated impact −2% to −4%. Private banking and lending revenue declined 13% as lower Marcus deposit margins offset higher balances.

Opportunities

  • Conversion of the investment-banking backlog: estimated impact +6% to +12%. Higher completed M&A and underwriting activity could extend the earnings recovery.
  • Scaling alternative investments: estimated impact +4% to +9%. Record fundraising and growing alternative assets could produce higher recurring and performance-related fees.
  • Expansion of financing and net-interest income: estimated impact +3% to +7%. Net-interest income increased 27%, while FICC and Equities financing reached record levels.
  • Further efficiency gains: estimated impact +3% to +6%. Continued revenue growth without equivalent fixed-cost expansion could keep the efficiency ratio below 60%.

Threats

  • Capital-markets normalization or economic contraction: estimated impact −15% to −25%. Weaker markets could affect trading, underwriting, M&A, investment gains and managed assets simultaneously.
  • Failure of the backlog to convert: estimated impact −4% to −8%. Goldman warns that backlog transactions may be delayed, modified or abandoned.
  • Regulatory and capital constraints: estimated impact −5% to −12%. The supplementary leverage ratio declined from 4.7% to 4.3%, and higher requirements could restrict balance-sheet growth or capital returns.
  • Credit normalization: estimated impact −5% to −10%. Q2 provisions were unusually low, leaving earnings exposed to higher wholesale, real-estate or consumer-related losses.
  • Premium-priced repurchases: estimated impact −3% to −7%. Goldman repurchased shares at an average $984.57, substantially above reported book value.

Valuation Scenarios

For Goldman, sustainable ROE and book value provide a better valuation foundation than mechanically multiplying one record quarter. We use reported book value of $367.67 and value the company under different assumptions for sustainable ROE, growth and shareholder return requirements.

Bear Scenario — $505

The bear case assumes that Q2 represents a favorable cyclical peak rather than a durable earnings level.

  • Probability: 20%
  • Sustainable ROE: 14%
  • Long-term book-value growth: 3%
  • Required shareholder return: 11%
  • Justified price-to-book ratio: 1.375 times
  • Calculated value: approximately $506
  • Rounded target: $505
  • Change from $1,152.07: approximately −56%

This outcome would be consistent with weaker trading and underwriting activity, slower backlog conversion and a return to mid-teens profitability.

Base Scenario — $860

The base case gives Goldman credit for a structurally improved franchise but normalizes the record Q2 performance.

  • Probability: 55%
  • Sustainable ROE: 18%
  • Long-term book-value growth: 4%
  • Required shareholder return: 10%
  • Justified price-to-book ratio: approximately 2.33 times
  • Calculated value: approximately $858
  • Rounded target: $860
  • Change from $1,152.07: approximately −25%

An 18% sustainable ROE is already a strong assumption. It recognizes the growth of Asset & Wealth Management, financing and recurring fees without assuming that every quarter matches Q2.

Bull Scenario — $1,390

The bull case assumes that Goldman can sustain returns close to its first-half 2026 performance.

  • Probability: 25%
  • Sustainable ROE: 22%
  • Long-term book-value growth: 5%
  • Required shareholder return: 9.5%
  • Justified price-to-book ratio: approximately 3.78 times
  • Calculated value: approximately $1,389
  • Rounded target: $1,390
  • Change from $1,152.07: approximately +21%

This requires continued banking-pipeline conversion, strong trading and financing activity, expanding recurring fees and a market willing to treat the earnings as more durable.

Probability-Weighted Fair Value

Applying the scenario probabilities produces a value of approximately $920 per share:

  • Bear contribution: $505 × 20% = $101
  • Base contribution: $860 × 55% = $473
  • Bull contribution: $1,390 × 25% = $347.50
  • Probability-weighted value: approximately $920

The percentage distinction is important. A $1,152 stock price is approximately 25% above a $920 fair value, but the shares would need to decline approximately 20% to reach that value.

Verdict

Goldman’s Q2 results justify a positive reassessment of the business. The firm generated record revenue, improved operating efficiency, expanded its banking backlog and continued building a larger recurring Asset & Wealth Management franchise. This was not a weak business temporarily rescued by one accounting adjustment.

Nevertheless, the post-earnings price already assumes an unusually favorable outcome. At $1,152.07, Goldman trades at approximately 3.13 times book value, 3.42 times tangible book value and 17.8 times trailing EPS.

Using a 10% required return and 4% long-term growth, the current price implies sustainable ROE of approximately 22.8%. That is almost identical to Q2’s 23.5% result. Investors are therefore being asked to treat an exceptional quarter as something close to Goldman’s durable earning power.

Our final fair value is $920 per share, with a reasonable range of $850 to $950. That valuation gives Goldman a substantial premium for franchise quality and improved profitability. It does not treat the company as an ordinary bank or assume a return to book value.

For a value investor, $920 represents fair value—not a fat-pitch price. At the current price, Goldman may continue rising if the bull case develops, but the margin of safety is limited and the downside becomes material if ROE normalizes.

Call to Action

Would you pay more than three times book value for Goldman Sachs if maintaining that valuation requires a sustainable ROE close to 23%?

The next quarters should answer three questions:

  • Does the investment-banking backlog convert into completed transactions and revenue?
  • Can Equities and financing remain strong without another exceptional market environment?
  • Can Asset & Wealth Management continue expanding recurring fees fast enough to reduce Goldman’s earnings cyclicality?

Follow SWOTstock for earnings analysis, independent valuation scenarios and updates as those assumptions are tested.

Disclaimer

This article is for informational and educational purposes only and does not constitute investment advice, a recommendation or an offer to buy or sell securities. The valuation scenarios depend on assumptions about sustainable profitability, growth and required returns. Actual results may differ materially. Investors should conduct their own research and consider their financial objectives, risk tolerance and circumstances before making investment decisions.
Bank of America Q2 2026 Earnings Analysis: Strong Core Banking Franchise Supports Higher Fair Value

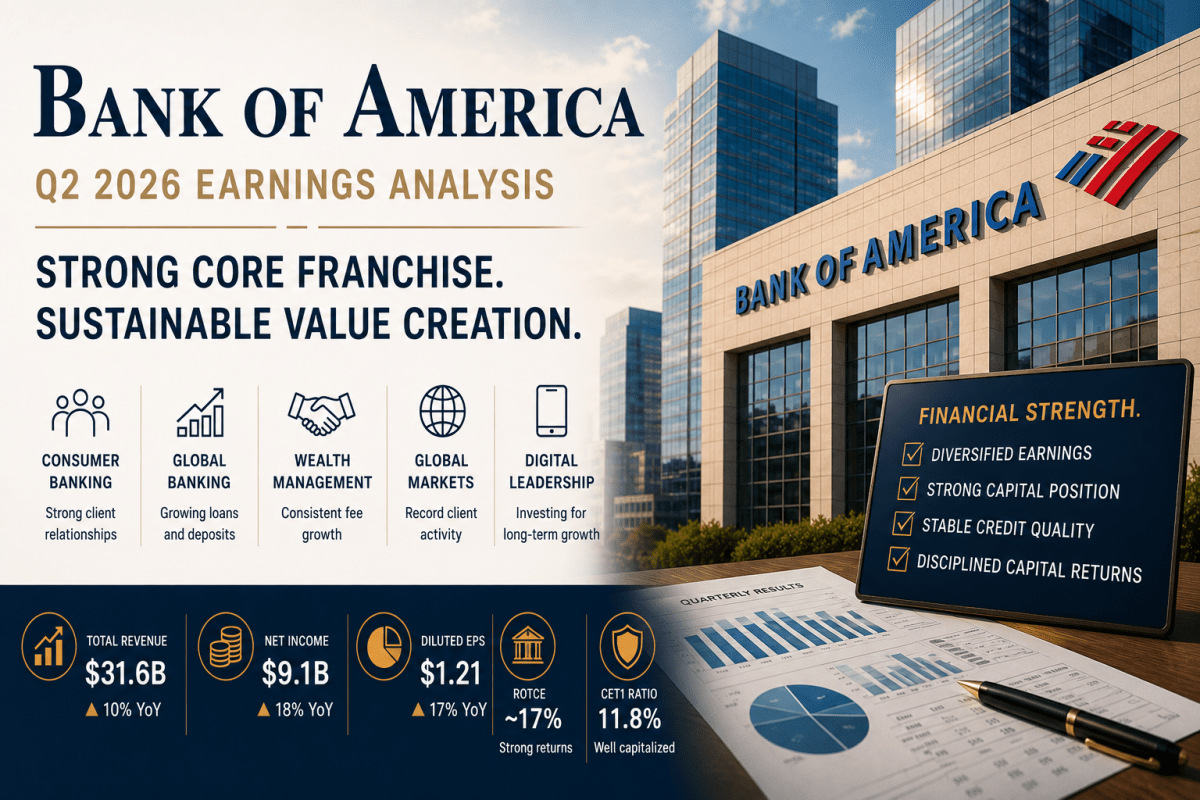
Bank of America reported a robust second quarter with revenues of $31.6 billion and net income of $9.1 billion, reflecting strong performance across its diverse business segments. Despite initial market caution, the company’s earnings stability and growth in net interest income suggest long-term resilience. The estimated fair value of shares is approximately $64.

TL;DR Summary

Bank of America (BAC:NYSE) delivered an impressive second quarter, reporting strong revenue and earnings growth driven by broad-based contributions across Consumer Banking, Wealth Management, Global Banking, and Global Markets. More importantly, the company’s core banking franchise continued to strengthen through growing net interest income, stable credit quality, and robust capital generation.

While the market initially reacted cautiously before the shares recovered during the trading session, our independent analysis suggests the quarter reinforced the long-term investment thesis rather than fundamentally changing it. We estimate a probability-weighted fair value of approximately $64 per share, indicating the stock is modestly undervalued but not yet a “fat pitch.”


Quarter Recap

Bank of America reported another strong quarter that highlighted the resilience of its diversified business model. Revenue reached $31.6 billion, while net income increased to $9.1 billion, resulting in diluted earnings per share of $1.21.

Unlike quarters where performance depends heavily on one business segment, Q2 demonstrated strength across multiple earnings engines. Consumer Banking continued to benefit from healthy client activity, Wealth Management generated steady fee income, Global Banking experienced improved commercial engagement, and Global Markets delivered strong client-driven trading results.

Perhaps more importantly for long-term investors, management reaffirmed confidence in net interest income growth and reported stable credit quality, suggesting that the company’s earnings strength extends beyond short-term market activity.


Key Highlights

  • Revenue increased to $31.6 billion.
  • Net income reached $9.1 billion.
  • Diluted EPS increased to $1.21.
  • Net interest income continued to grow, with management expecting full-year results toward the upper end of previous guidance.
  • ROTCE remained around 17%, demonstrating efficient capital utilization.
  • Consumer and commercial credit quality remained stable.
  • Capital ratios continued to support dividends, share repurchases, and future growth investments.

SWOT Analysis

Bank of America’s latest quarter reinforces the strength of one of the largest banking franchises in the United States. The company continues to benefit from a diversified earnings base, disciplined capital management, and a stable deposit franchise. However, banking remains inherently cyclical, and investors should continue monitoring interest rates, credit quality, and economic conditions.

Strengths

  • Diversified earnings franchise (+8% to +12%)
    • Strong contributions from Consumer Banking, Wealth Management, Global Banking, and Global Markets reduce dependence on any single business segment.
  • Growing core net interest income (+6% to +10%)
    • Continued NII growth reinforces the recurring earnings power of the core banking business.
  • Excellent profitability and capital efficiency (+5% to +8%)
    • ROTCE around 17% demonstrates strong returns on shareholder capital.
  • Strong capital position (+3% to +6%)
    • Healthy capital supports continued dividends, share repurchases, and resilience during economic downturns.
  • Stable credit quality (+2% to +5%)
    • No evidence of broad-based deterioration in the loan portfolio.

Weaknesses

  • Interest-rate sensitivity (-6% to -10%)
    • Future earnings remain influenced by changes in interest rates and deposit pricing.
  • Cyclical capital markets businesses (-4% to -8%)
    • Trading and investment banking revenues naturally fluctuate with market conditions.
  • Moderate long-term growth profile (-3% to -6%)
    • As a mature banking franchise, growth is expected to remain steady rather than rapid.

Opportunities

  • Continued investment banking recovery (+5% to +9%)
    • Improved corporate activity could further expand fee income.
  • Digital banking and AI productivity (+4% to +7%)
    • Ongoing technology investments should improve efficiency while strengthening customer relationships.
  • Higher shareholder returns (+3% to +6%)
    • Strong capital generation creates additional flexibility for dividends and share repurchases.

Threats

  • Economic slowdown and higher credit losses (-8% to -15%)
    • A recession would reduce loan demand while increasing credit costs.
  • Margin compression from lower interest rates (-6% to -10%)
    • Lower net interest income would reduce recurring earnings.
  • Regulatory changes (-3% to -7%)
    • Higher capital requirements could reduce future returns on equity.

Valuation Scenarios

Although Q2 demonstrated strong operating momentum, valuation should reflect both the quality of the franchise and the cyclical nature of banking. Rather than assuming today’s earnings represent either a permanent peak or a temporary anomaly, we evaluate three possible scenarios.

Bear Case — $52 (25%)

Assumes weaker net interest income, softer capital markets activity, modestly higher credit costs, and a lower valuation multiple.

Base Case — $64 (50%)

Assumes stable net interest income, healthy credit quality, continued profitability, and valuation multiples consistent with historical norms.

Bull Case — $74 (25%)

Assumes sustained earnings growth, continued strength across multiple business segments, accelerating shareholder returns, and modest valuation expansion.

Probability-Weighted Fair Value

Combining these scenarios produces a probability-weighted fair value of approximately $64 per share.


Verdict

Bank of America continues to demonstrate why it remains one of the highest-quality banking franchises in the United States. Its diversified earnings base, strong deposit franchise, disciplined capital allocation, and healthy balance sheet provide resilience across different economic environments.

Importantly, this conclusion is based primarily on the company’s official financial disclosures rather than market narratives or analyst opinions.

Following the earnings release, the market initially responded cautiously before the shares recovered later in the trading session. Our independent assessment suggests that investors ultimately recognized the quality of the quarter while continuing to evaluate the sustainability of future earnings.

At current prices, Bank of America appears modestly undervalued relative to our estimated intrinsic value of approximately $64 per share. While the valuation is attractive for long-term investors, it does not yet provide the wide margin of safety typically associated with a “fat pitch.”


Call to Action

Did you reach the same conclusion after reading Bank of America’s earnings report?

Do you believe the market is correctly valuing the company’s long-term earnings power, or is there still upside that investors have yet to recognize?

Share your thoughts in the comments, and follow SWOTstock for independent earnings analysis based on official company disclosures rather than market consensus.


Disclaimer

This article is intended for educational and informational purposes only and should not be considered financial advice or a recommendation to buy or sell any security. The analysis is based primarily on Bank of America’s official financial disclosures and management commentary, supplemented by independent valuation reasoning. Investors should conduct their own research and consider their individual financial circumstances before making investment decisions.

NVIDIA Q1 FY2027 Earnings: AI Infrastructure King Still Dominates — But Is the Market Starting to Question Sustainability?

NVIDIA reported Q1 FY2027 revenue of $81.6 billion, an 85% year-over-year increase, with Data Center revenue up 92%. Despite strong earnings, the stock fell, indicating investor concerns about sustaining AI infrastructure spending. The company’s strategic shift and ongoing growth suggest a promising future, but geopolitical risks and valuation questions remain.

TL;DR Summary

NVIDIA (NVDA:NASDAQ) delivered another extraordinary quarter, reporting Q1 FY2027 revenue of $81.6 billion, up 85% year over year, with Data Center revenue surging 92% to $75.2 billion. Blackwell deployment appears successful, enterprise AI adoption is broadening, and management continues positioning NVIDIA not merely as a chipmaker, but as the foundational infrastructure layer for the AI economy.

Yet despite the massive earnings beat, the stock declined after earnings. That reaction suggests the market is beginning to shift its focus from short-term growth toward a more difficult question: how sustainable is the current AI infrastructure spending cycle?

Our probability-weighted fair value estimate stands at approximately $266/share, with the market increasingly pricing NVIDIA as a long-duration AI platform rather than a traditional semiconductor company.


Quarter Recap

NVIDIA’s Q1 FY2027 results reinforced why the company remains the central player in the global AI boom.

Revenue reached $81.6 billion, growing 85% year over year and 20% sequentially. The Data Center segment once again dominated results, generating $75.2 billion in revenue, up 92% year over year. Gross margins remained extraordinarily strong at roughly 75%, while management also announced an additional $80 billion share repurchase authorization and raised the quarterly dividend.

Perhaps most importantly, management commentary strongly suggested that the transition from Hopper to Blackwell is progressing successfully. Earlier investor concerns about deployment bottlenecks, power constraints, and customer transition risks did not materialize in the quarter.

CEO Jensen Huang framed the AI buildout as “the largest infrastructure expansion in human history,” emphasizing NVIDIA’s long-term positioning across AI factories, networking, enterprise AI, robotics, and edge computing.

The company also revealed an important strategic shift: hyperscalers now represent roughly half of Data Center revenue, with the remaining demand increasingly coming from enterprise AI, sovereign AI projects, and AI-native cloud providers. That diversification helps reduce one of the major bear concerns surrounding customer concentration.

However, China export restrictions remain a meaningful headwind. NVIDIA disclosed that it had no Hopper shipments into China during the quarter, compared to billions of dollars of China-related revenue a year earlier.


Key Highlights

  • Revenue grew 85% year over year to $81.6 billion
  • Data Center revenue surged 92% to $75.2 billion
  • Blackwell deployment appears to be ramping successfully
  • Gross margins remained near 75%
  • NVIDIA authorized an additional $80 billion buyback
  • Dividend increased substantially
  • Enterprise and sovereign AI demand broadened beyond hyperscalers
  • China export restrictions remain a material geopolitical risk
  • Market reaction after earnings was negative despite strong operational performance

SWOT Analysis

NVIDIA’s latest quarter continues to demonstrate extraordinary operational strength. However, investors are increasingly debating whether the current valuation already assumes years of uninterrupted AI infrastructure expansion.

Strengths

  • NVIDIA remains the dominant AI infrastructure platform globally, supported by CUDA, NVLink, networking, and a deeply integrated ecosystem.
    • Estimated price impact: +15% to +25%
  • Data Center growth remains exceptional, with revenue up 92% year over year despite ongoing China restrictions.
    • Estimated price impact: +10% to +18%
  • Blackwell deployment appears successful, easing prior investor concerns around product transition risks.
    • Estimated price impact: +8% to +15%
  • Gross margins near 75% and enormous cash generation continue to separate NVIDIA from most semiconductor peers.
    • Estimated price impact: +5% to +12%
  • Demand is increasingly diversifying beyond hyperscalers into enterprise AI, sovereign AI, and industrial AI deployments.
    • Estimated price impact: +5% to +10%

Weaknesses

  • NVIDIA’s valuation already reflects extremely high expectations for long-term AI dominance.
    • Estimated price impact: -10% to -20%
  • Current growth remains heavily dependent on sustained AI infrastructure spending globally.
    • Estimated price impact: -8% to -18%
  • Hyperscaler concentration risk, while improving, remains meaningful.
    • Estimated price impact: -5% to -12%
  • The company faces constant pressure to flawlessly execute across Blackwell, Rubin, networking, and software ecosystems.
    • Estimated price impact: -5% to -10%

Opportunities

  • AI inference demand could eventually surpass training demand as enterprise AI agents become mainstream.
    • Estimated price impact: +15% to +30%
  • Robotics, autonomous systems, and physical AI represent potentially massive adjacent growth markets.
    • Estimated price impact: +10% to +25%
  • Enterprise AI adoption still appears to be in the early innings globally.
    • Estimated price impact: +10% to +20%
  • NVIDIA’s evolution into a full-stack AI infrastructure provider could strengthen its competitive moat further.
    • Estimated price impact: +8% to +18%

Threats

  • China export restrictions remain a significant geopolitical and revenue risk.
    • Estimated price impact: -10% to -20%
  • Hyperscalers continue developing custom AI chips that may reduce dependency on NVIDIA over time.
    • Estimated price impact: -8% to -18%
  • AI infrastructure spending could eventually enter a digestion phase after the current deployment boom.
    • Estimated price impact: -15% to -30%
  • Competition and eventual margin normalization may pressure valuation multiples in the future.
    • Estimated price impact: -5% to -15%
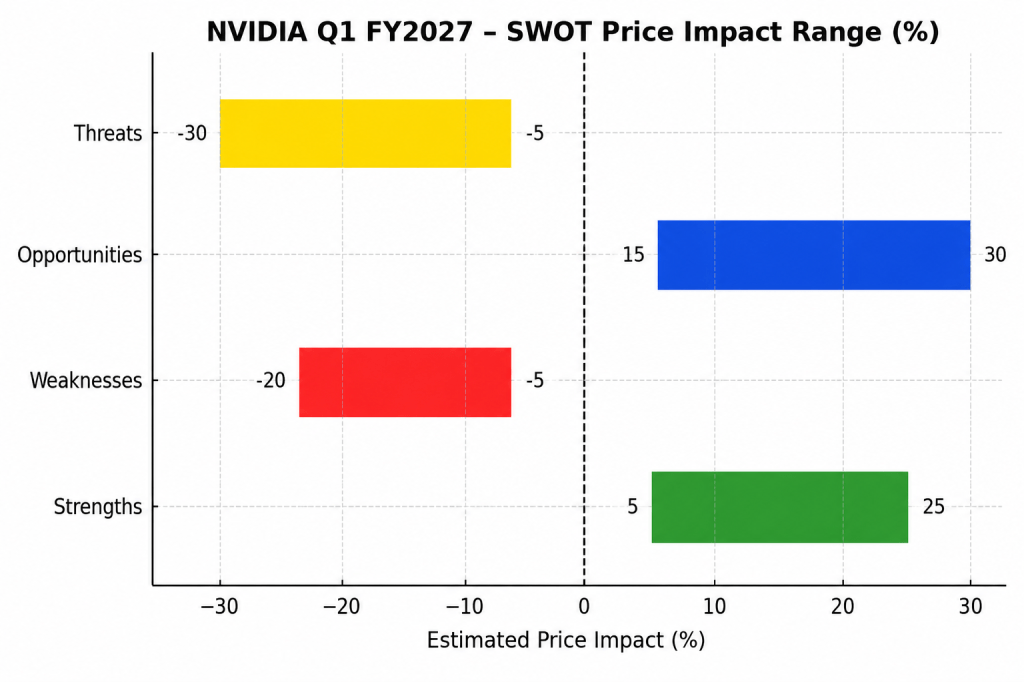
NVIDIA Q1 FY2027 SWOT price impact range chart showing strengths, weaknesses, opportunities, and threats with estimated percentage impacts on stock valuation following strong AI infrastructure earnings growth.
NVIDIA Q1 FY2027 SWOT analysis chart illustrating the estimated valuation impact ranges from AI infrastructure leadership, Blackwell deployment, enterprise AI expansion, valuation risks, and geopolitical threats.

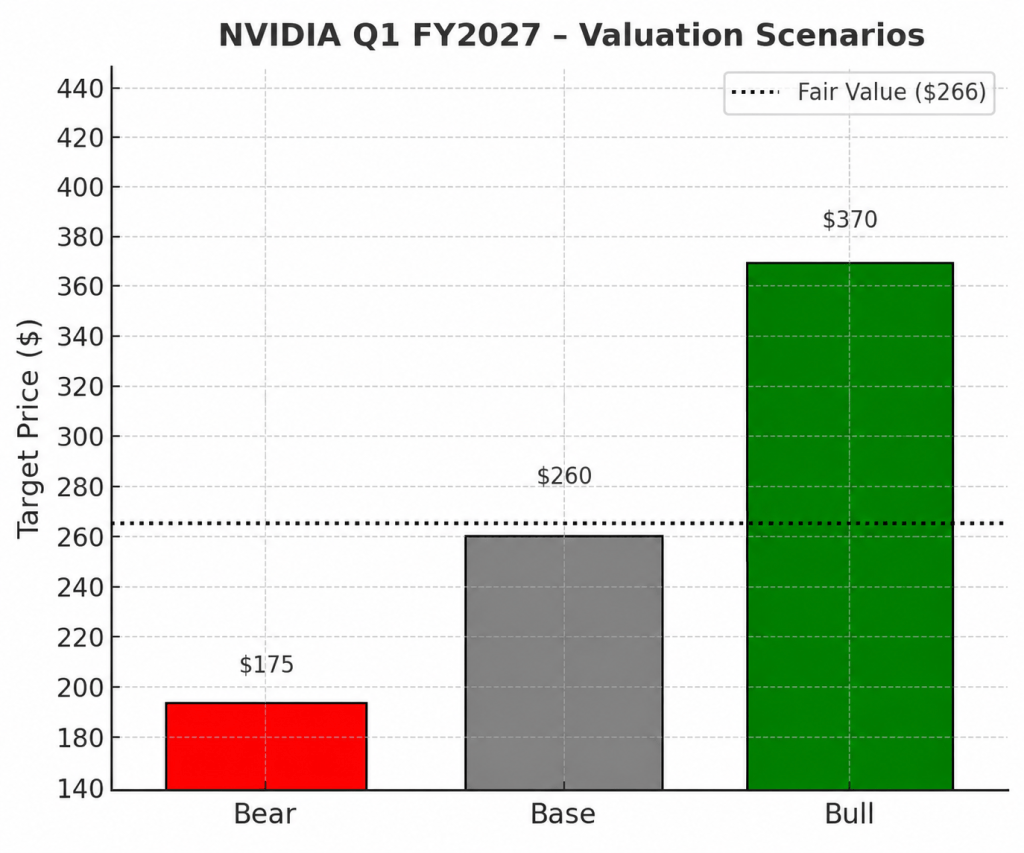
Valuation Scenarios

NVIDIA’s valuation increasingly depends on how long the AI infrastructure cycle continues and whether AI ultimately becomes a foundational layer of the global economy.

Bear Scenario

In the bear case, hyperscaler AI spending slows materially over the next several years as customers optimize deployed infrastructure and enterprise ROI proves slower than expected. Growth decelerates sharply, margins normalize lower, and valuation multiples compress.

  • Estimated fair value: $160–$190
  • Probability: 25%

Base Scenario

In the base case, AI infrastructure demand remains structurally strong but gradually moderates into a sustainable multi-year growth cycle. NVIDIA maintains leadership across AI compute, networking, and software ecosystems while enterprise AI adoption continues expanding globally.

  • Estimated fair value: $240–$280
  • Probability: 50%

Bull Scenario

In the bull case, AI evolves into a foundational global infrastructure layer comparable to cloud computing or the internet itself. Inference demand explodes, robotics and physical AI scale rapidly, and NVIDIA successfully becomes the operating platform for global AI infrastructure.

  • Estimated fair value: $320–$420
  • Probability: 25%

Based on these scenarios, our estimated probability-weighted fair value is approximately:

→ $266/share

NVIDIA Q1 FY2027 valuation scenarios chart showing bear, base, and bull case target prices with a probability-weighted fair value estimate of $266 per share.
NVIDIA Q1 FY2027 valuation scenario analysis comparing bear, base, and bull case price targets based on AI infrastructure demand sustainability, enterprise AI adoption, and long-term platform dominance potential.

Verdict

Operationally, NVIDIA still looks extraordinarily strong. The company continues to dominate the global AI infrastructure market, margins remain exceptional, and Blackwell deployment appears successful.

The market’s muted post-earnings reaction likely reflects a shift in investor psychology rather than disappointment in the quarter itself. Investors are beginning to ask whether the current pace of AI infrastructure spending can continue for many years and whether NVIDIA’s valuation already prices in near-perfect execution.

For long-term growth investors, NVIDIA still represents one of the highest-quality AI infrastructure companies globally. However, future returns may increasingly depend not only on continued strong growth, but on NVIDIA’s ability to justify its role as a long-duration AI platform rather than merely a cyclical semiconductor leader.


Call to Action

Do you think NVIDIA’s current valuation still underestimates the long-term AI opportunity, or is the market finally becoming more cautious about AI infrastructure sustainability?

Visit SWOTstock for more earnings breakdowns, SWOT analysis, and valuation scenarios focused on helping retail investors better understand the companies shaping the AI economy.


Disclaimer

This article is for informational and educational purposes only and does not constitute investment advice. Investors should conduct their own research and consider their financial situation and risk tolerance before making investment decisions.