Bank of America Q2 2025: Earnings Beat, Dividend Growth Ahead, and a Fair Value Play for Income Investors

TL;DR

Bank of America posted Q2 2025 EPS of $0.89, topping expectations, driven by record net interest income and robust trading revenue. Management reaffirmed NII guidance toward $15.5–$15.7 billion and announced an 8% dividend hike (raising forward yield to ~3.2%). While credit risks in commercial real estate and macro uncertainties persist, BAC remains fairly valued near $48, making it a steady, income‑oriented choice for DIY value investors.


Quarter Recap

In Q2 2025, Bank of America reported revenue of $26.6 billion (+4% YoY) with net interest income (NII) reaching $14.8 billion — a record high. Net income rose to $7.1 billion (EPS $0.89), beating estimates by 3 cents.

Management highlighted:

  • Efficiency progress: Non‑interest expenses dropped ~$600 million QoQ, with a target to reach ~60% efficiency ratio.
  • Deposit strength: 8th straight quarter of deposit growth, with average checking balances rising from $6K to $9.2K YoY.
  • Credit costs: Provisions increased to ~$1.6 billion, mainly from office‑related CRE loans.
  • Trading resilience: Markets revenue rose ~15% YoY, with management expecting a 13‑quarter growth streak to continue.
  • Shareholder returns: $7.3 billion in Q2 (dividends + buybacks) and an 8% dividend increase announced for Q3.

Key Highlights

  • EPS: $0.89 (+7% YoY), beat by 3 cents
  • Revenue: $26.6 billion (+4% YoY)
  • Net Interest Income: $14.8 billion (record)
  • Efficiency: Expenses down $600 million QoQ; targeting ~60% ratio
  • Dividend: 8% hike brings forward yield to ~3.2%
  • Asset quality: Net charge‑offs of $1.5 billion; provisions up to $1.6 billion
  • Deposits: 8th consecutive quarter of growth
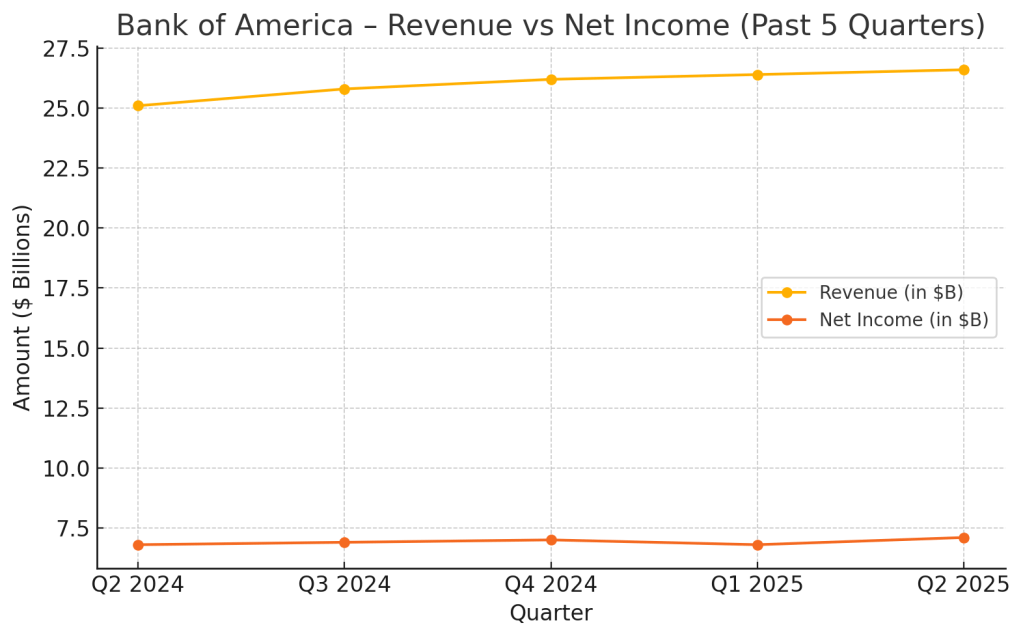
Line chart showing Bank of America revenue and net income over the past five quarters, highlighting Q2 2025 growth in both metrics.

SWOT Analysis

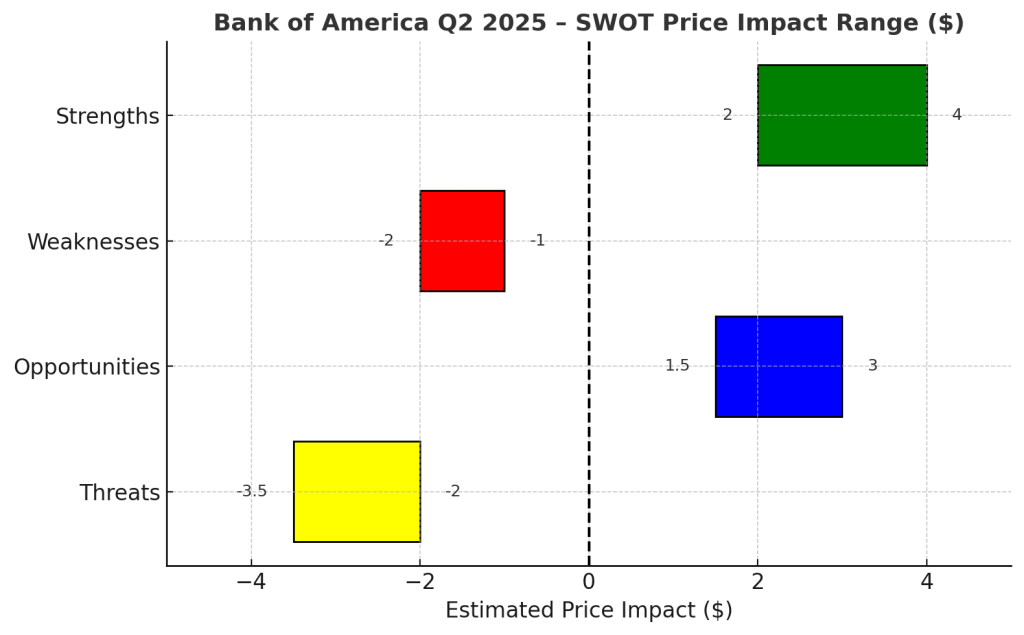
  • Strengths (+$2 – 4 impact):
    Record NII, diversified revenue streams, improving efficiency, and a dividend hike reflecting capital confidence.
  • Weaknesses (−$1 – 2 impact):
    Slower revenue growth than peers, elevated CRE‑related losses, and a still‑high expense base.
  • Opportunities (+$1.5 – 3 impact):
    AI & digital investments, sustained deposit momentum, expanding trading revenue, and higher dividend yield enhancing total return.
  • Threats (−$2 – 3.5 impact):
    Tariff‑driven macro risks, potential Fed rate cuts compressing NII, and rising credit costs in commercial real estate.

Net price impact: ≈ +$1.0–1.5/share vs. pre‑earnings levels, supporting the current range.


SWOT Summary Table

Bank of America Q2 2025 SWOT price impact analysis table showing strengths, weaknesses, opportunities, and threats with estimated stock price impacts.
Bar chart showing Bank of America Q2 2025 SWOT price impact ranges: strengths (+2 to +4), weaknesses (−1 to −2), opportunities (+1.5 to +3), and threats (−2 to −3.5), with X-axis starting at −5.

Valuation Scenarios

To frame a realistic outlook for Bank of America’s stock, we modeled three scenarios based on management’s guidance, Q2 results, and macro risks. The Base Case assumes steady EPS growth, stable net interest income, and controlled expenses, keeping the stock near its current range. The Bull Case reflects a scenario where trading revenue momentum accelerates, the efficiency ratio improves faster toward the 60% target, and net interest income benefits from a slower‑than‑expected pace of Fed rate cuts. Conversely, the Bear Case factors in higher commercial real estate charge‑offs and a compressed margin environment from rapid rate cuts. These scenarios give a clear range of plausible outcomes for value investors, balancing potential upside with key risks.

Bank of America Q2 2025 valuation scenarios table showing bull case at $52, base case at $48, and bear case at $42 with probability-weighted fair value of $48.

Probability‑Weighted Fair Value:(0.5 × 48) + (0.3 × 52) + (0.2 × 42) ≈ $48
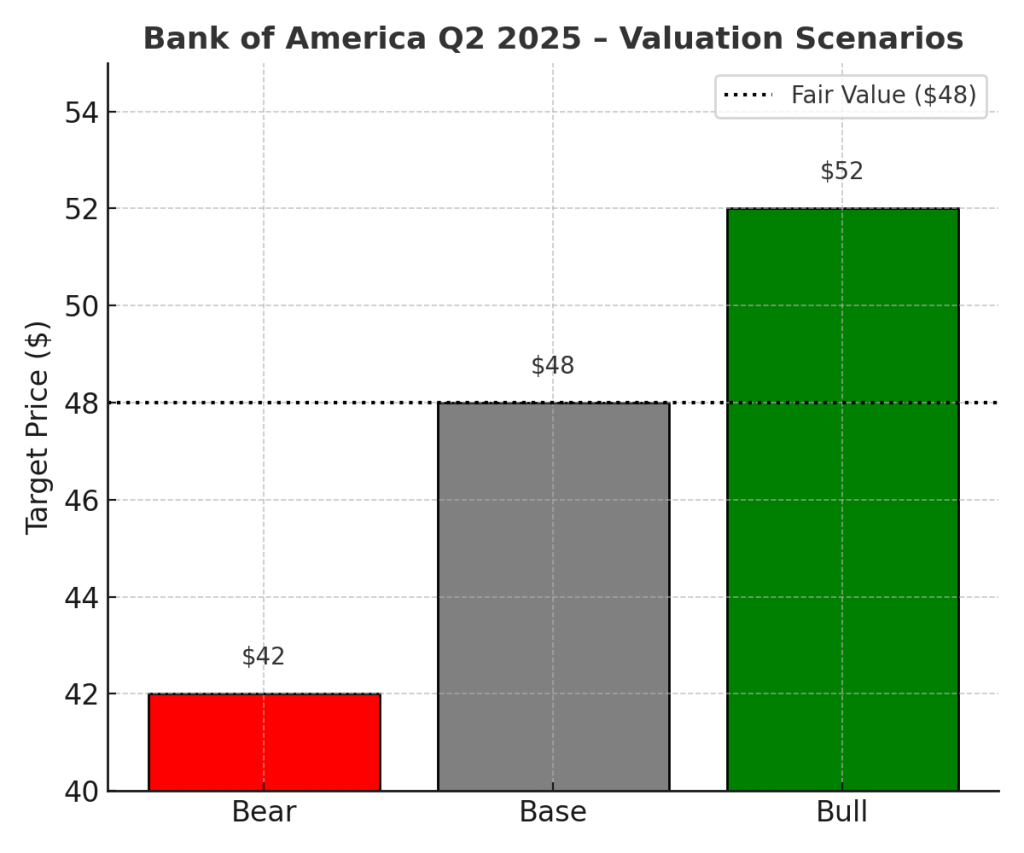
Bar chart showing Bank of America Q2 2025 valuation scenarios: Bear case at $42, Base case at $48, and Bull case at $52, with a dotted line for the $48 fair value.

Dividend Growth Snapshot

Bank of America’s 8% dividend hike for Q3 2025 raises the quarterly payout from $0.24 to $0.26 per share, pushing the forward yield to roughly 3.2% at current prices. This increase continues the bank’s consistent multi‑year trend of dividend growth, reflecting management’s confidence in earnings stability and capital strength. Combined with $7.3 billion in share buybacks during Q2, this makes BAC a compelling choice for income‑focused investors who prioritize reliable cash returns and long‑term capital appreciation.

  • Q2 dividend: $0.24/share → Q3: $0.26/share
  • 8% increase = forward yield of ~3.2% at $48/share

Peer Comparison

When compared to its large‑cap U.S. banking peers, Bank of America sits in the middle of the pack. At a price‑to‑book ratio of ~1.3× and forward P/E around 13×, it trades cheaper than JPMorgan (P/B ~1.6×, P/E ~12×) but at a premium to Citigroup (P/B ~0.8×, P/E ~9×). Dividend yield at ~3.2% (post‑hike) makes BAC more attractive than JPMorgan (~2.8%) but still below Citi’s ~4%. This positioning reflects its balanced profile: steadier than Citi, but with less growth momentum than JPMorgan — a mix that appeals to value‑oriented investors seeking income without extreme risk exposure.

Peer comparison table for Bank of America Q2 2025 versus JPMorgan and Citigroup, showing price-to-book, price-to-earnings, and dividend yield metrics.

Verdict

At ≈$48/share, BAC trades close to our fair value estimate. For DIY value investors, it offers steady dividends, aggressive buybacks, and a resilient balance sheet. While upside is modest without macro support, the dividend hikeand sustained trading & deposit growth make it a hold‑to‑accumulate for long‑term portfolios.


Call to Action

Do you hold Bank of America or other bank stocks? Comment below — is BAC your top pick for steady income, or do you prefer peers like Citi or JPMorgan?


Disclaimer

This analysis is for informational purposes only and based solely on Bank of America’s official Q2 2025 financial report and earnings call. It does not constitute financial advice. Please consult a licensed advisor before making investment decisions.

AI and the Social Cost of Disruption: How Big Tech’s Bold Bets Can Build a Future for Everyone

Big Tech is betting billions on AI and data centers — but will these investments drive shared growth or deepen divides? Here’s what history tells us, and what needs to change.

AI is changing everything — and faster than any technology before it.

Google, Microsoft, Amazon, and Meta are spending tens of billions on AI and data centers, betting big on a future where intelligent systems power every part of business and life. Alphabet alone has raised its 2025 CapEx guidance to $85 billion — the biggest single‑year infrastructure push in its history.

This is thrilling — but it’s also unsettling.

Because history tells us that when technology moves this fast, people and communities often get left behind.


We’ve Seen This Before

AI may feel new, but the playbook isn’t.

  • 1980s: Robots transformed auto plants. Companies promised “upskilling,” but Rust Belt towns were hollowed out.
  • 1990s: Office computers streamlined workflows. Administrative jobs shrank. New IT careers emerged — but in different cities, for different people.
  • 2000s: The internet created digital giants and e‑commerce while wiping out thousands of brick‑and‑mortar businesses.

Every time, it’s the same two‑step:

  1. Phase 1: Use new tech to cut costs and boost margins.
  2. Phase 2: Eventually reinvest the gains to create new industries and jobs — often far away from those disrupted by Phase 1.

AI’s SWOT: Where We Stand Today

Looking at this AI revolution through a SWOT lens:

Strengths:
Big Tech has the scale, cash, and vision to reimagine industries. Google is reshaping search with AI Overviews. Microsoft wants Copilot in everything. Amazon is transforming logistics and the cloud. They’re building capabilities that could change how the world works.

Opportunities:
These investments could unlock entirely new markets — AI‑driven enterprise services, personalized tools, and products we can’t yet imagine. If done right, this could spark another tech‑driven growth era, creating jobs and opportunities across the economy.

Weaknesses:
The spending is enormous — Alphabet’s CapEx jumped 70% YoY — and it’s based on a bet that demand for AI will match the scale of these build‑outs. If enterprise adoption slows or ROI disappoints, this could become overcapacity, not innovation.

Threats:
The social cost is already visible: layoffs in tech, finance, and operations. Productivity gains are flowing to shareholders and elite talent — not the communities losing jobs. Political backlash is building. Regulators are circling. And if the economy slows — tariffs, inflation, geopolitical shocks — these bold bets could quickly look like overreach.


Why This Matters Beyond Big Tech

This isn’t just a Silicon Valley story.

  • Communities are hollowing out. The jobs being cut aren’t coming back to the same towns.
  • Wealth is concentrating. AI’s early gains are flowing to the top — executives, shareholders, and highly skilled tech workers.
  • Politics are polarizing. Resentment over lost livelihoods is fueling unrest and hardening divisions worldwide.

AI isn’t the cause of these divides — but it’s accelerating them.


The Choice Ahead

Here’s the good news: this doesn’t have to end the way previous tech disruptions did.

Big Tech can choose to:

  • Reinvest productivity gains into building new industries and creating meaningful roles for displaced workers.
  • Upskill employees so they can thrive in an AI‑powered economy instead of being left behind by it.
  • Partner with communities and governments to make AI adoption a growth engine for more than just shareholders.

This isn’t about slowing innovation. It’s about making sure progress works for more than a few.


Bottom Line

AI is the boldest bet Big Tech has made in decades. It has the potential to change everything — how we work, how we live, how we create.

But if these investments remain focused only on efficiency and cost‑cutting, they won’t just disrupt industries. They’ll deepen inequality, fuel resentment, and harden the divides already pulling societies apart.

If instead they’re used to build new opportunities for more people, AI could be remembered not as a disruptor, but as the engine of a new era of shared growth.

That choice is still on the table.


What do you think? Are these bold AI investments building a better future for everyone — or just for a few?


Leave a comment


Alphabet Q2 2025 Earnings: AI Momentum vs. Rising CapEx — Is GOOGL Still a Buy?

Alphabet’s Q2 2025 earnings beat expectations with 14% revenue growth, soaring cloud margins, and AI‑driven engagement. Is GOOGL fairly valued or poised for more upside? Read our full SWOT and valuation analysis.

TL;DR

Alphabet delivered Q2 2025 revenue of $96.4B (+14% YoY) and EPS of $2.31 (+22% YoY), driven by AI‑powered engagement across Search and YouTube, and a Google Cloud margin jump to 20.7%. However, CapEx surged 70% YoY to $22.4B (guidance raised to $85B), raising near‑term cash flow concerns. Our probability‑weighted fair value: ~$195/share, suggesting GOOGL is fairly valued with modest upside.


Quarter Recap: Alphabet’s AI‑Fueled Growth

Alphabet beat expectations across the board:

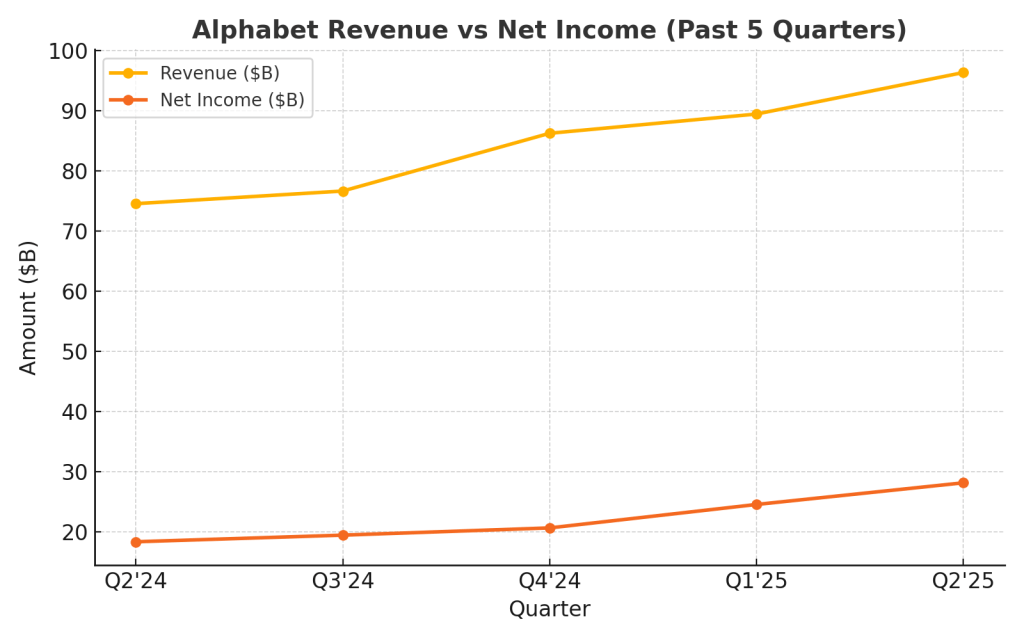
  • Revenue: $96.43B (+14% YoY)
  • Net Income: $28.2B (+19% YoY)
  • EPS: $2.31 (+22% YoY)
  • Google Services: $82.5B (+12%), driven by Search & YouTube.
  • YouTube Ads: $9.8B (+13% YoY); Shorts monetization now equals in‑stream levels.
  • Google Cloud: $13.62B (+32% YoY) with 20.7% operating margin, nearly doubling YoY.
  • CapEx: $22.4B (↑70% YoY), FY25 guidance lifted to $85B for AI/cloud data centers.

CEO Sundar Pichai emphasized AI as “positively impacting every part of the business.” He highlighted that $250M+ Google Cloud deals doubled YoY, showcasing enterprise AI traction.


Key Highlights from Q2

  • AI at Scale: AI Overviews hit 2B+ monthly users; AI Mode reached 100M+ monthly users in the U.S. & India.
  • Enterprise Momentum: Cloud operating margin doubled to 20.7%, with stronger large‑scale enterprise deals.
  • Subscription Growth: Platforms & Devices up 20% YoY, enhancing recurring revenue streams.
  • Regulatory Watch: Q2 included $1.4B in legal costs; DOJ antitrust rulings could progress later this year.
  • AI Talent Retention: Pichai addressed competitive pressures, reaffirming Alphabet’s “ability to attract and retain top‑tier researchers.”
  • Search Trade‑offs: AI Overviews may reduce ad click rates in some verticals — management is testing new ad formats to offset this.
Line chart showing Alphabet’s revenue and net income for the past five quarters, highlighting strong growth with Q2 2025 revenue at $96.4 billion and net income at $28.2 billion.

SWOT Analysis (With Price Impact)

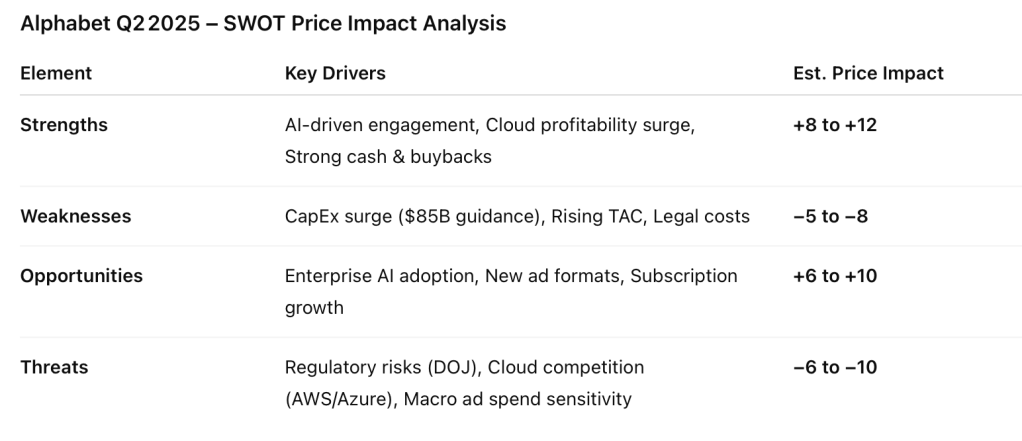
Strengths (+$8 to +$12):

  • AI products deepening Search & YouTube engagement.
  • Cloud at 20.7% margin, $50B+ annualized revenue run‑rate.
  • Strong cash position ($95B) and shareholder returns ($13.6B buybacks, $2.5B dividends).

Weaknesses (–$5 to –$8):

  • FY25 CapEx raised to $85B, weighing on free cash flow.
  • Rising TAC (traffic acquisition costs) and operating expenses.
  • Elevated legal expenses impacting profitability.

Opportunities (+$6 to +$10):

  • Enterprise adoption of Gemini AI models and Google Cloud solutions.
  • AI‑driven Search and YouTube monetization enhancements.
  • Subscription and device growth for stable recurring revenue.

Threats (–$6 to –$10):

  • DOJ antitrust remedies may reshape Search monetization.
  • Intense competition from AWS & Azure in enterprise AI.
  • Ad spend vulnerability during macroeconomic slowdowns.

SWOT Price Impact Table

SWOT analysis table for Alphabet Q2 2025 showing key drivers and estimated price impact for strengths, weaknesses, opportunities, and threats.
Horizontal bar chart showing Alphabet Q2 2025 SWOT price impact ranges: Strengths (+8 to +12) in green, Weaknesses (−8 to −5) in red, Opportunities (+6 to +10) in blue, and Threats (−10 to −6) in yellow, with a vertical zero line for reference.

Valuation Scenarios

Valuation scenarios table for Alphabet Q2 2025 with target prices and probabilities

Fair Value Calculation (12‑month outlook)

From the valuation scenarios:

  • Bull: $225 × 30% = $67.5
  • Base: $192 × 50% = $96.0
  • Bear: $156 × 20% = $31.2

Weighted Fair Value=67.5+96.0+31.2=194.7Weighted Fair Value=67.5+96.0+31.2=194.7

Rounded: ≈ $195 per share

Vertical bar chart showing Alphabet Q2 2025 valuation scenarios: Bear case at $156 (20% probability) in red, Base case at $192 (50% probability) in gray, and Bull case at $225 (30% probability) in green, with a dotted line indicating the fair value at $195.

Verdict

At $192, Alphabet is fairly valued, offering limited short-term upside but strong long-term growth potential if AI-driven monetization plays out as management anticipates. Growth-focused investors may see this as an attractive hold for AI & cloud exposure; value-focused investors may prefer to wait for a wider margin of safety.


Call to Action

Are you positioning for Alphabet’s AI-powered future? Share your thoughts — is GOOGL a buy, hold, or wait for a dip?


Disclaimer

This analysis is for informational purposes only and based solely on Alphabet’s official Q2 2025 financial report and earnings call. It does not constitute financial advice.


Leave a comment