
TL;DR
Micron Technology (NASDAQ:MU) another extraordinary quarter.
Fiscal Q4 2026 revenue reached $54.23 billion, non-GAAP EPS rose to $33.42, and non-GAAP gross margin reached 87.0%. Management expects the momentum to continue, guiding fiscal Q1 2027 revenue to approximately $61.5 billionand non-GAAP EPS to $38.15 ± $1.00.
More importantly, the investment thesis is becoming about more than one exceptional memory cycle. Micron’s expanding AI exposure, HBM demand and longer-term customer commitments provide increasing evidence that the company’s earnings profile may be structurally stronger than in previous memory cycles.
But valuation remains difficult.
Current profitability is extraordinary, and simply annualizing Q1 guidance would imply roughly $152.60 of EPS—an assumption that would be too aggressive to treat as normalized earnings.
Our analysis instead uses approximately $120 of normalized EPS and a conservative 10× multiple, producing a working fair value of approximately $1,200 per share, with a reasonable valuation range of roughly $1,100–$1,300.
The central question for investors is no longer whether Micron’s business has improved.
It has.
The question is how much of today’s extraordinary profitability can persist when memory supply eventually catches up with demand.
Quarter Recap
Micron reported record fiscal fourth-quarter and full-year 2026 results.
Q4 revenue reached $54.23 billion, increasing 31% sequentially. Non-GAAP EPS reached $33.42, compared with $25.11 in Q3.
Non-GAAP gross margin expanded to 87.0%.
The results also substantially exceeded Micron’s previous Q4 guidance:
- Revenue guidance had been $50.0 billion ± $1.0 billion.
- Non-GAAP EPS guidance had been $31.00 ± $1.00.
- Actual revenue reached $54.23 billion.
- Actual non-GAAP EPS reached $33.42.
For the full fiscal year, Micron generated:
- Revenue of $133.19 billion
- Non-GAAP EPS of $75.52
- Operating cash flow of $89.68 billion
- Adjusted free cash flow of $62.31 billion
But trailing FY2026 EPS understates Micron’s current earnings power because profitability accelerated dramatically during the year.
At the same time, investors should be careful not to make the opposite mistake and assume Q4 profitability represents a permanent new baseline.
Key Highlights
FY2027 begins from an exceptionally strong position
Micron guides fiscal Q1 2027 to:
- Revenue of $61.5 billion ± $1.5 billion
- Non-GAAP gross margin of approximately 86.25%
- Non-GAAP EPS of $38.15 ± $1.00
Annualizing that EPS mechanically would produce approximately $152.60.
That is useful for understanding Micron’s current earnings run rate, but it should not automatically be treated as sustainable earnings power.
Data center has become central to Micron
Cloud Memory generated approximately $16.3 billion of Q4 revenue, while Core Data Center generated approximately $18.0 billion.
Combined, those businesses represented roughly 63% of quarterly revenue.
Core Data Center gross margin reached approximately 90%.
Data-center SSD revenue approached $10 billion, demonstrating that Micron’s AI opportunity extends beyond HBM.
HBM continues to strengthen the AI thesis
Micron reported that HBM revenue grew faster than overall company revenue.
The company has agreements covering the vast majority of its calendar-2027 HBM bit supply, strengthening demand visibility.
Micron is also working with NVIDIA on a customized HBM4E implementation known as NVHBM for next-generation GPU and NVLink Fusion platforms.
Strategic Customer Agreements could change Micron’s cyclicality
Micron now has 26 Strategic Customer Agreements.
Management estimates these agreements represent more than 35% of revenue through 2030.
Customer financial commitments have reached approximately $32 billion, while qualifying agreements represent roughly $150 billion of remaining performance obligations.
If these agreements meaningfully stabilize volumes and pricing through future downturns, they could reduce one of the biggest historical weaknesses of Micron’s business: extreme memory-cycle volatility.
Supply remains tight—but investment is accelerating
Management expects memory supply-demand conditions to remain tight through 2027 and 2028.
However, Micron is also increasing capital expenditure substantially.
Q1 FY2027 capex is expected around $11.5 billion, with first-half spending around $25 billion and still higher investment expected during the second half.
Much of this additional construction will not translate into production capacity until late 2028 and beyond, but investors should nevertheless watch whether today’s extraordinary profitability eventually stimulates enough industry investment to recreate the traditional memory cycle.
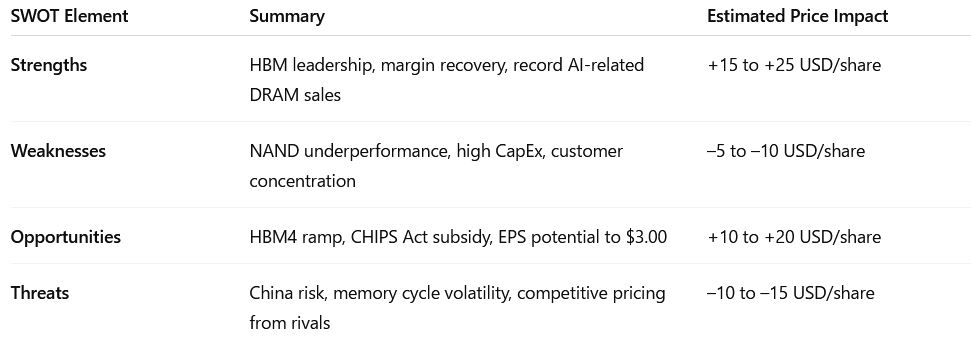
SWOT Analysis
Micron’s investment case has strengthened considerably. AI has increased the strategic importance of memory, HBM and data-center storage are improving product mix, and long-term customer agreements could reduce historical cyclicality.
The principal risk is no longer weak demand. It is whether investors extrapolate today’s exceptional pricing and margins too far into the future.
Strengths
- Extraordinary current earnings power — estimated price impact: +15% to +25%.
- Q4 EPS reached $33.42 and Q1 guidance rises to $38.15 ± $1.00.
- Micron is producing exceptional operating leverage from current memory conditions.
- AI memory positioning — +15% to +30%.
- HBM, advanced server DRAM and enterprise SSDs place Micron directly inside the AI infrastructure buildout.
- Improving revenue visibility — +15% to +25%.
- Strategic Customer Agreements provide longer-duration volume commitments and pricing frameworks that could reduce earnings volatility.
- Exceptional financial capacity — +5% to +10%.
- Strong operating cash flow and free cash flow give Micron substantial capacity to finance manufacturing expansion.
Weaknesses
- Difficulty normalizing profitability — −15% to −30%.
- An 87% gross margin is extraordinary for a memory manufacturer and should not automatically be extrapolated indefinitely.
- Capital intensity — −10% to −15%.
- Maintaining technology and manufacturing leadership requires enormous ongoing investment.
- Memory concentration — −10% to −15%.
- Micron remains heavily dependent on DRAM and NAND supply-demand conditions.
Opportunities
- Continued AI infrastructure expansion — +20% to +35%.
- Increasing memory content per AI system could sustain demand growth even as accelerator volumes expand.
- Structural change in memory economics — +15% to +30%.
- Long-term customer agreements and improved industry discipline could make future earnings materially less cyclical.
- Higher-value product mix — +10% to +20%.
- HBM, advanced DRAM and enterprise SSDs can improve the quality of Micron’s revenue mix.
Threats
- Future memory oversupply — −25% to −40%.
- Exceptional industry profitability creates powerful incentives for additional capacity.
- AI infrastructure normalization — −20% to −35%.
- Slower hyperscaler investment could reduce demand growth and pricing power.
- Competitive response — −15% to −25%.
- Samsung and SK hynix remain formidable competitors with substantial manufacturing capabilities.
- Peak-margin risk — −20% to −30%.
- Earnings could decline materially simply from memory-price normalization, even without a recession.
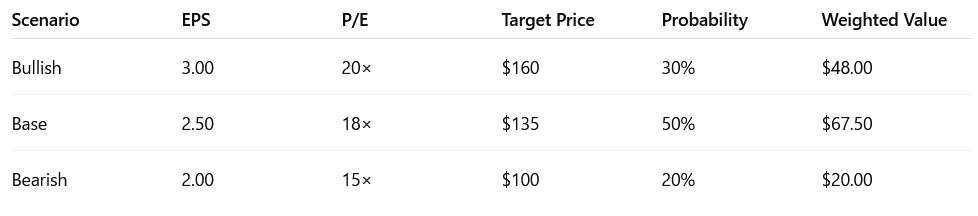
Valuation Scenarios
Micron is unusually difficult to value because trailing FY2026 EPS understates current earnings power, while annualizing Q1 guidance risks capitalizing potentially peak-cycle profitability.
We therefore value Micron using different assumptions about normalized earnings, rather than simply extrapolating the latest quarter.
Bear Case — approximately $720
- Normalized EPS: approximately $90
- Valuation multiple: approximately 8×
- Implied value: $720
This scenario assumes today’s extreme memory pricing eventually normalizes substantially.
AI and Strategic Customer Agreements prevent Micron from returning to historical trough economics, but the company remains fundamentally cyclical and investors continue applying a discounted multiple.
Probability: 25%
Base Case — approximately $1,200
- Normalized EPS: approximately $120
- Valuation multiple: approximately 10×
- Implied value: $1,200
This assumes that Micron’s economics have genuinely improved but today’s extraordinary margins are not permanent.
AI memory demand remains strong, HBM and data-center products improve mix, and long-term customer agreements reduce—but do not eliminate—memory cyclicality.
Probability: 50%
Bull Case — approximately $1,800
- Normalized EPS: approximately $150
- Valuation multiple: approximately 12×
- Implied value: $1,800
This scenario assumes that AI infrastructure demand remains exceptionally strong and that Strategic Customer Agreements fundamentally improve the durability of Micron’s earnings.
Under this scenario, current earnings power becomes closer to a sustainable baseline rather than peak-cycle profitability.
Probability: 25%
Probability-Weighted Fair Value
Applying these probabilities:
- Bear: $720 × 25% = $180
- Base: $1,200 × 50% = $600
- Bull: $1,800 × 25% = $450
The resulting probability-weighted fair value is approximately $1,230 per share.
Given the uncertainty surrounding normalized memory profitability, we prefer to think in terms of a fair-value zone of approximately $1,100–$1,300, rather than treating $1,230 as a precise intrinsic value.
Verdict
Micron’s Q4 FY2026 report strengthens the fundamental investment thesis.
The company isn’t merely benefiting from higher conventional memory prices. AI infrastructure is changing its product mix, HBM demand remains strong, data-center storage has become increasingly important, and long-term customer agreements could make future earnings more predictable.
That deserves recognition in Micron’s normalized earnings and valuation.
But investors should distinguish between a better business and permanently extraordinary economics.
An 87% gross margin and quarterly EPS approaching $40 are exceptional numbers. The principal valuation risk is assuming those conditions continue indefinitely.
Our working fair value is therefore approximately $1,200 per share, with a broader reasonable range of roughly $1,100–$1,300.
At around the $1,065 market price observed immediately following the earnings release, Micron trades modestly below our central fair-value estimate—but not at a large margin of safety.
For a growth investor, the most important evidence to watch now isn’t simply whether Micron beats the next quarter.
It is whether the company can demonstrate that $110–$125 or more of annual earnings power remains sustainable as memory supply eventually expands.
If that happens, Micron’s structural re-rating may have further to go.
If today’s profitability primarily reflects temporary scarcity, valuation risk remains substantial despite an exceptional business outlook.
Call to Action
Micron’s transformation from a traditional cyclical memory producer toward a strategic supplier of AI infrastructure is becoming increasingly difficult to ignore.
But how much of today’s earnings should investors treat as sustainable?
Follow SWOTstock as we continue tracking Micron’s HBM growth, Strategic Customer Agreements, memory supply conditions, capital expenditure and normalized earnings power through FY2027.
Disclaimer
This article is for informational and educational purposes only and does not constitute investment advice, financial advice, or a recommendation to buy or sell any security.
The valuation scenarios presented are based on assumptions and estimates derived from publicly available company information. Actual results may differ materially. Investors should conduct their own research and consider their individual financial circumstances, investment objectives and risk tolerance before making investment decisions.




Leave a Reply